What is a Mortgage APR Calculator?
The annual percentage rate is the cost of your loan expressed as a yearly rate, and in the United States it is not a marketing figure — it is defined in law. Regulation Z, which implements the Truth in Lending Act, prescribes exactly how it must be computed. This calculator implements that method: the actuarial method of 12 CFR Part 1026, Appendix J.
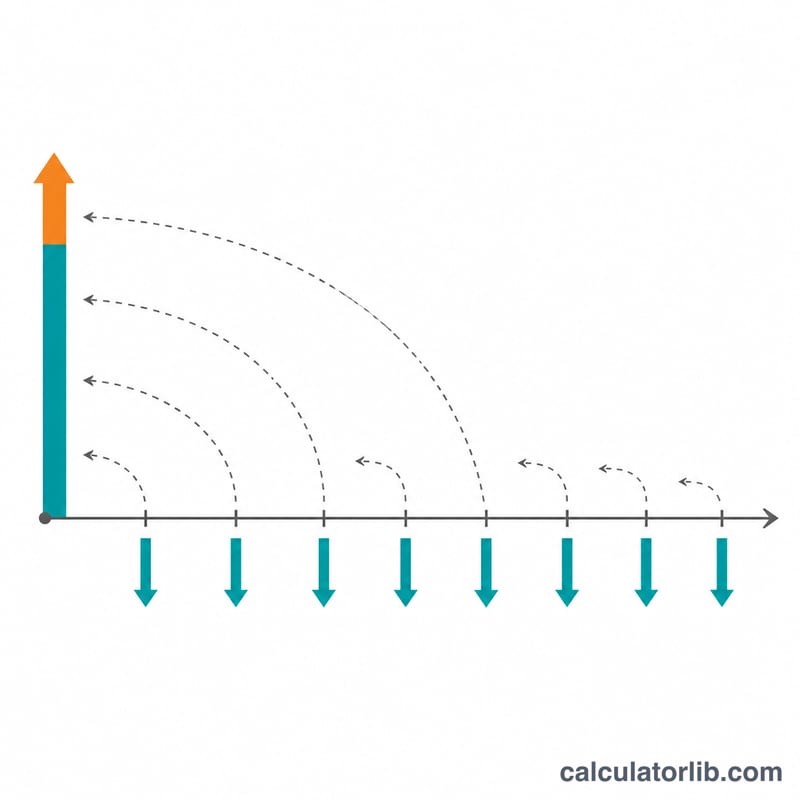
Your interest rate prices the money you borrowed. Your APR prices the money you actually received. When you pay points or an origination fee, those are withheld from the proceeds — you pay interest on money that never reached you. That gap is what the APR captures, and it is why the APR on a real mortgage is always higher than the note rate.
When to Use It
- Comparing two loan offers where one has a lower rate but higher points.
- Checking a Loan Estimate: the APR box on page 3 is computed this way, and it is legally accurate only within ±0.125 percentage points.
- Understanding why a "no-fee" loan at a higher rate can be cheaper than a low-rate loan with two points.
Which fees count
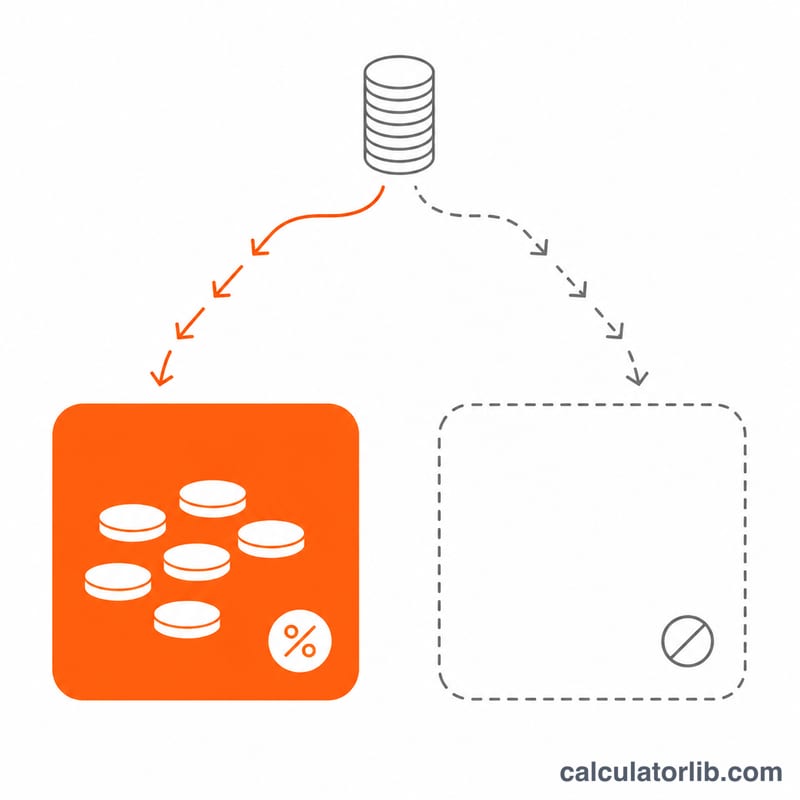
This is where most calculators go wrong, and they go wrong in both directions. A charge counts only if it is both a finance charge and prepaid — paid before or at closing, or withheld from the proceeds (12 CFR 1026.2(a)(23)). Points, origination and underwriting fees, prepaid interest and the mortgage insurance premium count. Bona fide and reasonable title, appraisal, credit-report and escrow fees are specifically excluded (12 CFR 1026.4(c)(7)).
Entering every closing cost will overstate your APR just as surely as entering none will understate it.
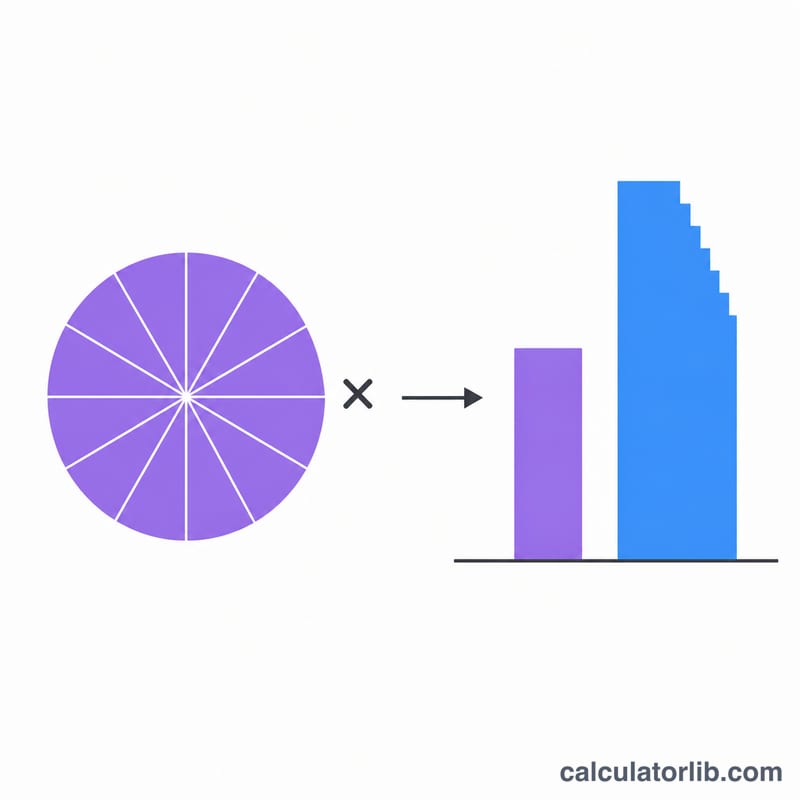
Why the APR is higher than your interest rate: points and other prepaid finance charges are withheld from what you actually receive, so you pay interest on money you never got. Reg Z prices that by solving for the rate that equates your payments to the amount advanced — not the amount borrowed. It uses the actuarial method of 12 CFR 1026 Appendix J. A disclosed APR is legally accurate within ±0.125 percentage points for a regular transaction (12 CFR 1026.22(a)(2)).
Why "nominal" matters
Appendix J requires the APR to be the nominal annual rate: the monthly rate multiplied by twelve. It is not compounded. This is the opposite of the European APRC, which is an effective annual rate — the same three letters, two different numbers. A calculator that compounds is not slightly off; it is answering a different jurisdiction's question.
Central bank policy rates today
The latest official policy rates of major central banks, updated automatically — the benchmark that bank deposit and loan rates follow.
- Federal Reserve · United States
- 3.75–4.00%
- As of
- 2026-11-13
- Change in 1 year
- 0 pp
Latest change Up +25 bp Federal Reserve changed its rate on 2026-09-17: from 3.50–3.75% to 3.75–4.00%.
| Central bank | Policy rate | As of | Change in 1 year |
|---|---|---|---|
| Banco Central do Brasil (Selic) · Brazil | 13.75% | 2026-11-16 | −1.25 pp |
| Banco de México · Mexico | 6.25% | 2026-11-10 | −1.00 pp |
| Federal Reserve · United States | 3.75–4.00% | 2026-11-13 | 0 pp |
| ECB | 2.50% | 2026-11-16 | +0.50 pp |
| Sveriges Riksbank · Sweden | 2.00% | 2026-11-16 | +0.25 pp |
| Saudi Central Bank (SAMA) · Saudi Arabia | 4.50% | 2026-10-29 | 0 pp |
| Reserve Bank of Australia · Australia | 4.60% | 2026-10-31 | +1.00 pp |
| Central Bank of the Republic of Türkiye · Türkiye | 36.00% | 2026-11-06 | −3.50 pp |
| Bank of Russia · Russia | 14.00% | 2026-11-10 | −2.50 pp |
| People’s Bank of China · China | 3.00% | 2026-11-10 | 0 pp |
| Bank of Canada · Canada | 2.50% | 2026-11-13 | +0.25 pp |
| Reserve Bank of India · India | 5.50% | 2026-10-19 | 0 pp |
| Bank of England · United Kingdom | 4.00% | 2026-11-16 | 0 pp |
| Bank of Japan · Japan | 1.25% | 2026-11-10 | +0.75 pp |
| Bank of Korea · South Korea | 3.00% | 2026-11-02 | +0.50 pp |
Federal Reserve: key rates and overnight market rates
The rates that frame monetary policy and the overnight market rate they steer, each with the date of its latest published value.
| Rate | Level | As of | Change in 1 year |
|---|---|---|---|
| Federal funds target range | 3.75–4.00% | 2026-11-13 | 0 pp |
| Effective federal funds rate (EFFR) | 3.88% | 2026-11-13 | 0 pp |
| Secured Overnight Financing Rate (SOFR) | 3.90% | 2026-11-13 | −0.10 pp |
Each rate keeps the date of its own latest published value; overnight market rates are published on the next business day.
Latest figure: 2026-11-13 Data last updated 2026-11-16 · current
Source: Banco Central do Brasil ODbL; Bank for International Settlements (BIS) Terms of permitted use of BIS statistics; Federal Reserve Bank of New York New York Fed Terms of Use; Board of Governors of the Federal Reserve System Public domain (U.S. government work); European Central Bank ECB reuse policy; Sveriges Riksbank Riksbank open data terms; The World Bank Group CC BY 4.0; Reserve Bank of Australia 2026 RBA copyright terms (Cash Rate); Bank of Canada Bank of Canada terms of use; Bank of England Open Government Licence v3.0
The one-year change is computed by CalculatorLib from these data. The EFFR and SOFR are subject to the Terms of Use posted at newyorkfed.org. The New York Fed is not responsible for publication of the EFFR and SOFR by CalculatorLib, does not sanction or endorse any particular republication, and has no liability for your use.
Source details and methodology
- Banco Central do Brasil
- Bank for International Settlements (BIS) — Central bank policy rates
- Federal Reserve Bank of New York — Reference rates (EFFR, SOFR)
- Board of Governors of the Federal Reserve System
- European Central Bank
- Sveriges Riksbank
- The World Bank Group — World Development Indicators (FR.INR.LEND, FR.INR.RINR)
- Reserve Bank of Australia 2026
- Bank of Canada
- Bank of England