What is an Annuity Payout?
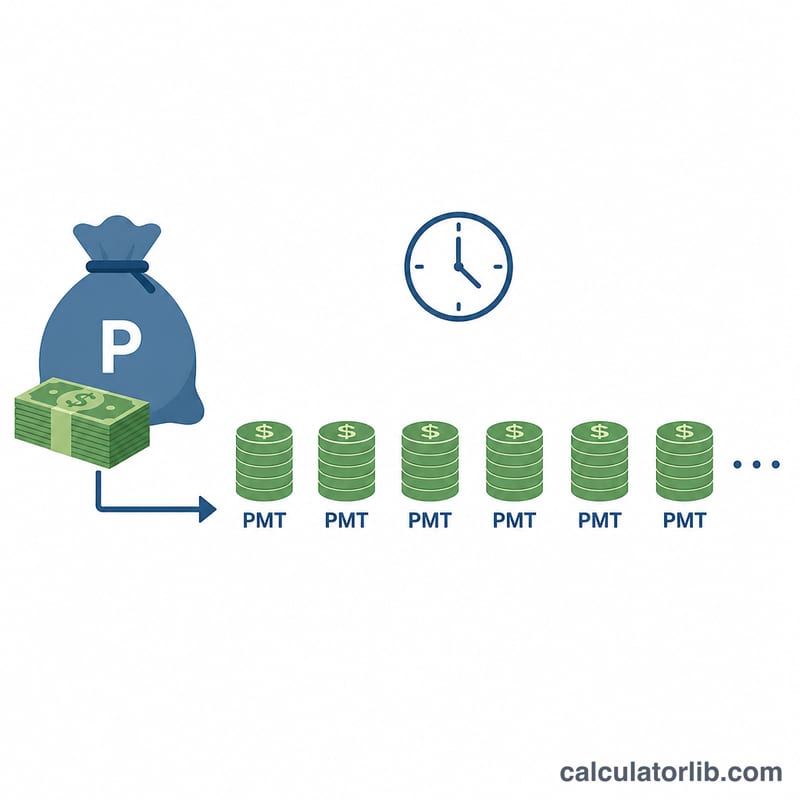
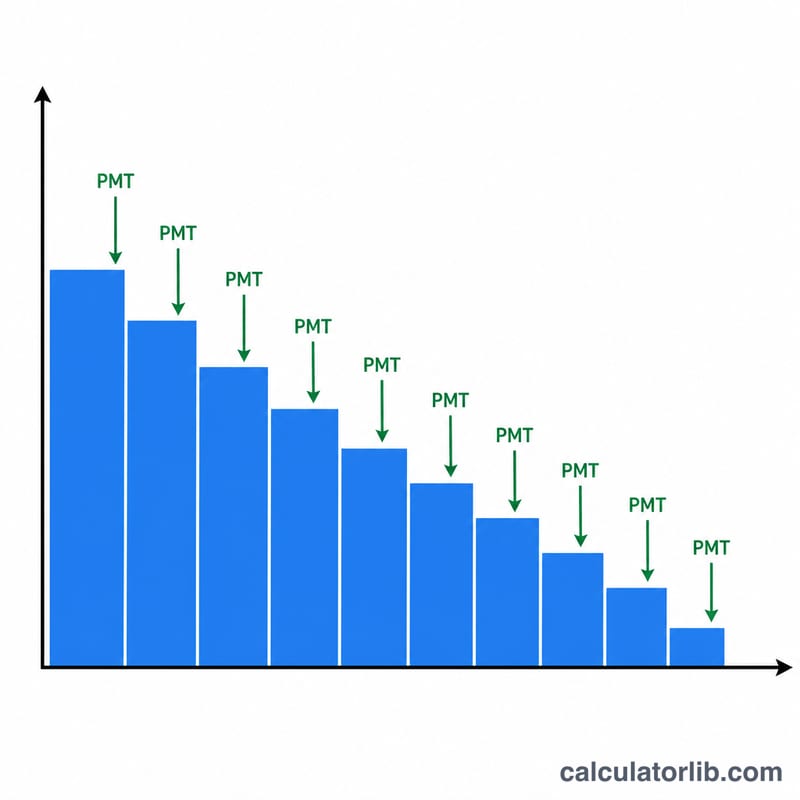
An annuity payout is a stream of regular withdrawals from a lump sum that earns interest. You start with a principal balance, the balance accumulates interest each period, and you draw a fixed amount at fixed intervals until the principal is depleted. This calculator answers two complementary questions: given a payout horizon, how much can you withdraw each period; or given a target periodic withdrawal, how long will the principal last?
Two Calculation Modes
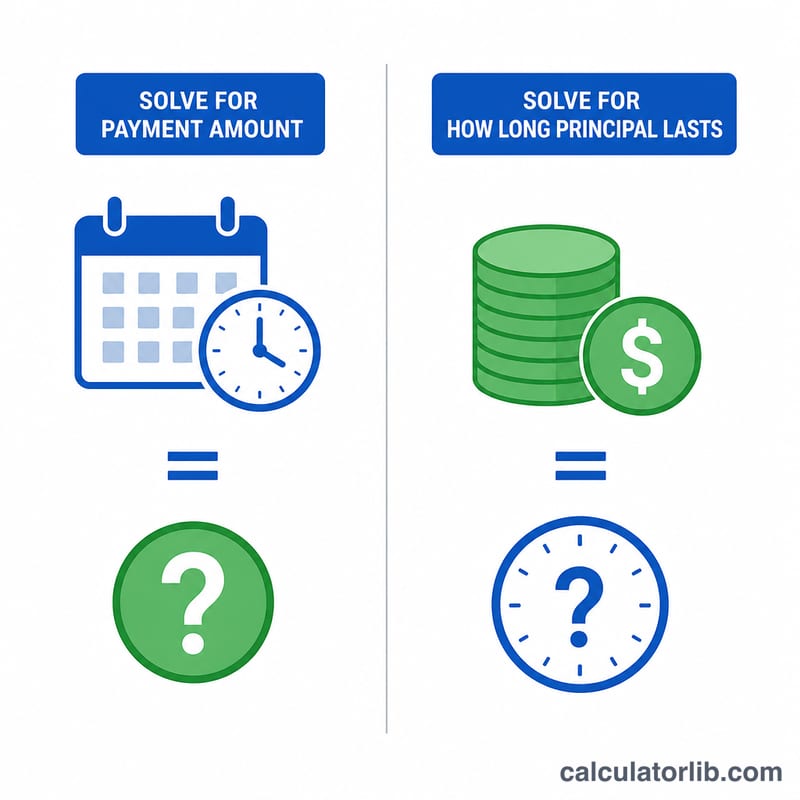
- Periodic Payout (Fixed Length): You decide how many years the payouts should last. The calculator returns the largest periodic amount that drains the principal exactly at the end of that horizon.
- Length (Fixed Payment): You decide how much to withdraw each period. The calculator returns the number of years the principal will support, including any final partial payment.
Pay Frequency
Higher pay frequency — e.g., monthly vs. annually — produces slightly higher total payouts because each withdrawal occurs sooner, leaving less principal to grow. The frequency options on this calculator follow standard financial conventions:
- Annually (1 payment/year), Semiannually (2), Quarterly (4)
- Monthly (12), Semimonthly (24, two payments per month), Biweekly (26, every two weeks)
Periodic Interest Rate
The annual interest rate must be converted to a per-period rate before payouts are calculated. This calculator uses the annual compounding convention (matching standard annuity tables): a 6% annual rate compounded once per year becomes a periodic rate of approximately 0.487% for monthly payments, not 0.5%.
$$i = (1 + r)^{1/n} - 1$$
where \(r\) is the annual rate (decimal) and \(n\) is the number of payments per year.
The Annuity Formula
The present-value-of-annuity formula relates the principal to the periodic payment, periodic rate, and number of periods (\(N = \text{years} \times n\)):
$$P = \text{PMT} \times \frac{1 - (1 + i)^{-N}}{i}$$
Solving for PMT (Fixed Length mode) gives the periodic payout. Solving for N (Fixed Payment mode) gives the number of periods, which divided by frequency yields the number of years.
Worked Example
Start with $500,000 at 6% annual interest, paid monthly over 10 years:
- Periodic rate $$i = (1.06)^{1/12} - 1 \approx 0.004868$$
- Number of periods $$N = 10 \times 12 = 120$$
- Periodic payout $$\text{PMT} = 500{,}000 \times \frac{0.004868}{1 - 1.06^{-10}} \approx \$5{,}511.20$$
- Total of 120 payments \(\approx \$661{,}344\)
- Total interest earned \(\approx \$161{,}344\)
Annuity vs. Self-Managed Withdrawal
This calculator models a deterministic annuity: a fixed interest rate and a fixed payout schedule. In practice, retirees often manage withdrawals from a portfolio of stocks, bonds, and cash whose returns vary year to year. Such "sequence of returns" risk — suffering a market drop in early withdrawal years — is the single biggest threat to a portfolio's longevity. The 4% rule and Monte Carlo retirement simulators address that variability; the annuity formula here assumes a smooth, guaranteed return.
Tax Considerations
If the principal is held in a tax-deferred account (traditional IRA, 401(k)), each withdrawal is taxable as ordinary income at your marginal rate — the displayed payout is pre-tax. Roth IRA withdrawals (after age 59½ and 5-year seasoning) and after-tax brokerage interest are taxed differently. Commercial annuities sold by insurance companies may also have surrender charges, mortality fees, and tax treatment that this calculator does not model.
Inflation Risk
A constant nominal payout loses purchasing power year by year. At 3% inflation, $5,511 today buys what about $4,094 buys in 10 years — a 26% reduction in real terms. To preserve real income, retirees often combine an annuity with inflation-indexed assets (TIPS, equities) or choose an inflation-adjusted annuity contract whose payment rises annually but starts lower than a fixed-payment annuity of equal cost.
Key Terms & Variables
- Principal (\(P\))
- The starting balance available at the beginning of the payout phase — the lump sum being drawn down.
- Periodic payment (\(\text{PMT}\))
- The fixed amount withdrawn each period that exactly exhausts the principal (plus accrued interest) by the end of the horizon.
- Annual rate (\(r\))
- The stated yearly interest rate, in percent, that the unwithdrawn balance continues to earn.
- Periodic rate (\(i\))
- The rate applied each payment period, \(i = (1+r/100)^{1/n}-1\), so that compounding over \(n\) periods reproduces the effective annual rate.
- Payments per year (\(n\), or \(m\))
- The payout frequency: 1 (annually), 2 (semiannually), 4 (quarterly), 12 (monthly), 24 (semimonthly), or 26 (biweekly).
- Total periods (\(N\))
- The total number of withdrawals, \(N = \text{years}\times n\).
- Payout horizon
- The span of time, in years, over which the principal is intended to be distributed.
- Present value of an annuity
- The lump sum today that is financially equivalent to a stream of future payments — here it equals the principal, since \(P = \text{PMT}\cdot\dfrac{1-(1+i)^{-N}}{i}\).
Interpreting Your Result
When you solve for the payment, the result is the largest level withdrawal that leaves the account at exactly zero after the final payment. Each period the balance earns interest at rate \(i\), the payment is subtracted, and at the horizon's end the principal is fully depleted — no money is left over and none runs short.
Payout frequency has a modest effect on the total. Because more frequent withdrawals pull money out slightly earlier, less interest accrues per dollar, but the effective annual rate is held constant, so the differences between, say, monthly and biweekly payouts are small. In general a higher frequency means a marginally higher cumulative total only when interest conventions differ; with a fixed effective annual rate the totals stay very close.
When you instead solve for length — how long the principal lasts at a chosen withdrawal — the horizon usually does not land on a whole number of periods. The reported duration therefore includes a smaller final partial payment that uses up whatever balance remains after the last full withdrawal.
Finally, all figures are pre-tax and are not adjusted for inflation. A fixed payment loses purchasing power over time, so a $2,400 monthly payout in year 1 buys less in year 20. To gauge that erosion, compare your payout against an inflation measure, and remember that withdrawals from tax-deferred annuities may be taxable as ordinary income. This is general information, not tax or financial advice — consult a qualified professional for your situation.
Central bank policy rates today
The latest official policy rates of major central banks, updated automatically — the benchmark that bank deposit and loan rates follow.
- Federal Reserve · United States
- 3.75–4.00%
- As of
- 2026-11-13
- Change in 1 year
- 0 pp
Latest change Up +25 bp Federal Reserve changed its rate on 2026-09-17: from 3.50–3.75% to 3.75–4.00%.
| Central bank | Policy rate | As of | Change in 1 year |
|---|---|---|---|
| Banco Central do Brasil (Selic) · Brazil | 13.75% | 2026-11-16 | −1.25 pp |
| Banco de México · Mexico | 6.25% | 2026-11-10 | −1.00 pp |
| Federal Reserve · United States | 3.75–4.00% | 2026-11-13 | 0 pp |
| ECB | 2.50% | 2026-11-16 | +0.50 pp |
| Sveriges Riksbank · Sweden | 2.00% | 2026-11-16 | +0.25 pp |
| Saudi Central Bank (SAMA) · Saudi Arabia | 4.50% | 2026-10-29 | 0 pp |
| Reserve Bank of Australia · Australia | 4.60% | 2026-10-31 | +1.00 pp |
| Central Bank of the Republic of Türkiye · Türkiye | 36.00% | 2026-11-06 | −3.50 pp |
| Bank of Russia · Russia | 14.00% | 2026-11-10 | −2.50 pp |
| People’s Bank of China · China | 3.00% | 2026-11-10 | 0 pp |
| Bank of Canada · Canada | 2.50% | 2026-11-13 | +0.25 pp |
| Reserve Bank of India · India | 5.50% | 2026-10-19 | 0 pp |
| Bank of England · United Kingdom | 4.00% | 2026-11-16 | 0 pp |
| Bank of Japan · Japan | 1.25% | 2026-11-10 | +0.75 pp |
| Bank of Korea · South Korea | 3.00% | 2026-11-02 | +0.50 pp |
Federal Reserve: key rates and overnight market rates
The rates that frame monetary policy and the overnight market rate they steer, each with the date of its latest published value.
| Rate | Level | As of | Change in 1 year |
|---|---|---|---|
| Federal funds target range | 3.75–4.00% | 2026-11-13 | 0 pp |
| Effective federal funds rate (EFFR) | 3.88% | 2026-11-13 | 0 pp |
| Secured Overnight Financing Rate (SOFR) | 3.90% | 2026-11-13 | −0.10 pp |
Each rate keeps the date of its own latest published value; overnight market rates are published on the next business day.
Latest figure: 2026-11-13 Data last updated 2026-11-16 · current
Source: Banco Central do Brasil ODbL; Bank for International Settlements (BIS) Terms of permitted use of BIS statistics; Federal Reserve Bank of New York New York Fed Terms of Use; Board of Governors of the Federal Reserve System Public domain (U.S. government work); European Central Bank ECB reuse policy; Sveriges Riksbank Riksbank open data terms; The World Bank Group CC BY 4.0; Reserve Bank of Australia 2026 RBA copyright terms (Cash Rate); Bank of Canada Bank of Canada terms of use; Bank of England Open Government Licence v3.0
The one-year change is computed by CalculatorLib from these data. The EFFR and SOFR are subject to the Terms of Use posted at newyorkfed.org. The New York Fed is not responsible for publication of the EFFR and SOFR by CalculatorLib, does not sanction or endorse any particular republication, and has no liability for your use.
Source details and methodology
- Banco Central do Brasil
- Bank for International Settlements (BIS) — Central bank policy rates
- Federal Reserve Bank of New York — Reference rates (EFFR, SOFR)
- Board of Governors of the Federal Reserve System
- European Central Bank
- Sveriges Riksbank
- The World Bank Group — World Development Indicators (FR.INR.LEND, FR.INR.RINR)
- Reserve Bank of Australia 2026
- Bank of Canada
- Bank of England