What This Calculator Does
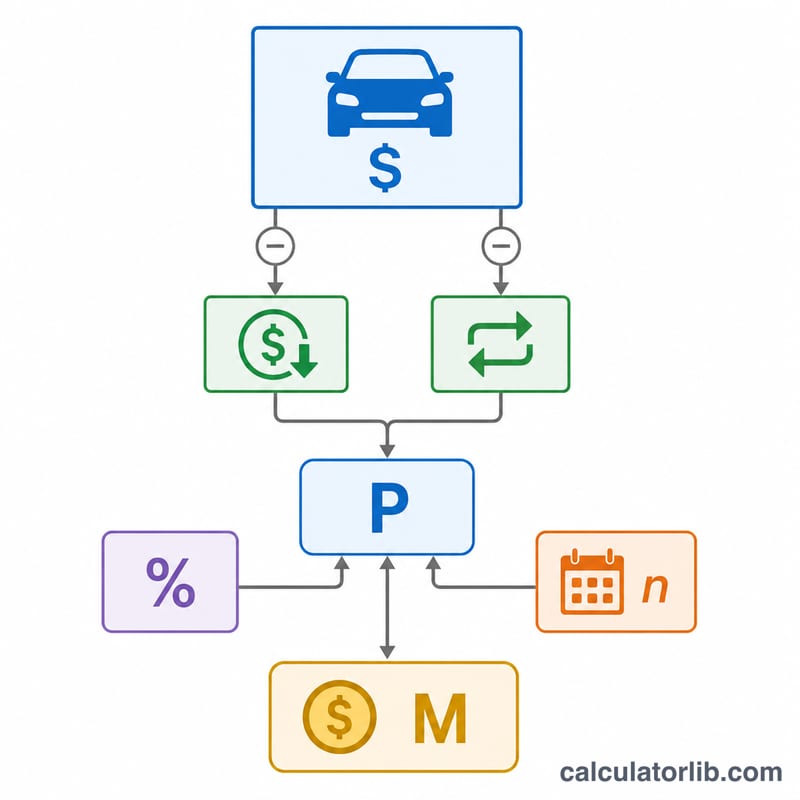
The Car Loan Payment Calculator estimates the fixed monthly payment for an auto loan based on the price of the vehicle, your down payment, any trade-in credit, the annual percentage rate (APR), and the loan term in months. It also shows the total amount you will repay and the total interest cost over the life of the loan, so you can compare offers and budget with confidence.
How to Use It
Enter the vehicle price, then subtract value by entering a down payment and trade-in amount. Type the APR your lender quoted and choose your loan term in months (common terms are 36, 48, 60, and 72 months). The calculator instantly returns your estimated monthly payment along with the amount financed, total of payments, and total interest.
The Formula Explained
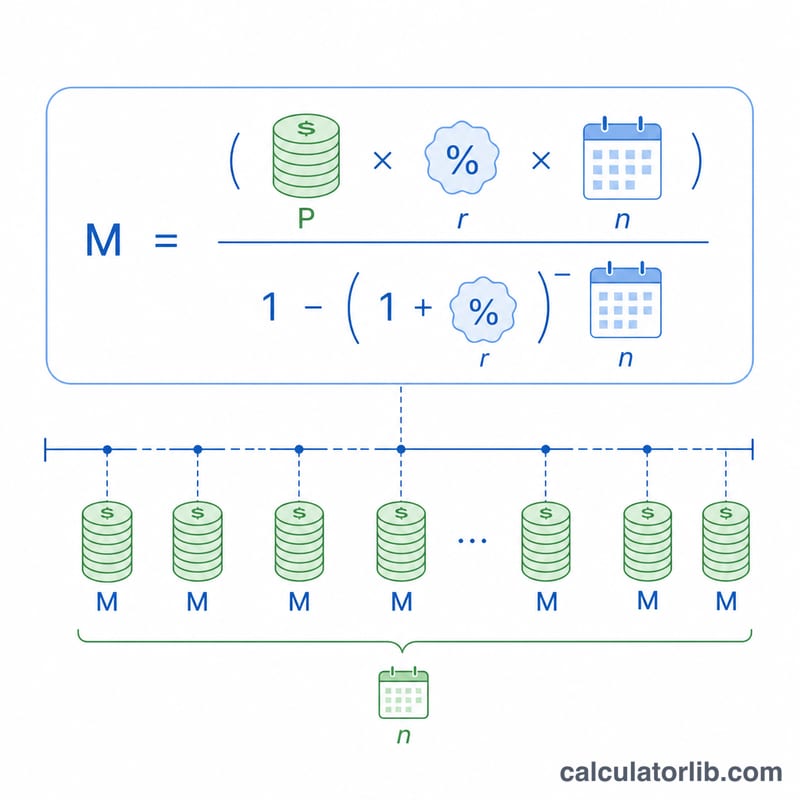
The standard amortized loan payment formula is $$ M = \frac{P \cdot r (1+r)^n}{(1+r)^n - 1} $$. Here P is the amount financed (price minus down payment and trade-in), r is the monthly interest rate (APR divided by 12, expressed as a decimal), and n is the number of monthly payments. When the APR is 0%, the payment is simply the principal divided by the number of months.
Worked Example
Suppose you buy a $30,000 car with a $5,000 down payment and no trade-in, financing $25,000 at 6% APR over 60 months. The monthly rate is \( 0.06 / 12 = 0.005 \). Plugging in gives a monthly payment of about $483.32, a total of payments around $28,999.20, and roughly $3,999.20 in interest.
Comparing Loan Terms and APRs Side by Side
The tables below use a financed amount (principal) of $25,000 and the standard amortization formula \(M = P\cdot\frac{r(1+r)^{n}}{(1+r)^{n}-1}\), where \(r\) is the APR divided by 12 (as a decimal) and \(n\) is the number of monthly payments. Payments are rounded to the cent; total paid is the rounded payment × number of months, and total interest is total paid minus $25,000. Figures assume a fixed rate, no fees rolled into the loan, and payments made monthly in arrears.
Different terms at a fixed 6% APR
| Term | Monthly payment | Total interest | Total paid |
|---|---|---|---|
| 36 months | $760.55 | $2,379.80 | $27,379.80 |
| 48 months | $587.13 | $3,182.24 | $28,182.24 |
| 60 months | $483.32 | $3,999.20 | $28,999.20 |
| 72 months | $414.32 | $4,831.04 | $29,831.04 |
| 84 months | $365.21 | $5,677.64 | $30,677.64 |
Stretching the term from 36 to 84 months lowers the monthly payment by roughly $395, but it more than doubles the total interest.
Different APRs at a 60-month term
| APR | Monthly payment | Total interest | Total paid |
|---|---|---|---|
| 4% | $460.41 | $2,624.60 | $27,624.60 |
| 6% | $483.32 | $3,999.20 | $28,999.20 |
| 8% | $506.91 | $5,414.60 | $30,414.60 |
| 10% | $531.18 | $6,870.80 | $31,870.80 |
Each 2-percentage-point rise in APR adds roughly $23–$24 to the monthly payment and well over $1,000 in total interest on this loan. Actual lender quotes may differ slightly because of rounding conventions, payment timing, and fees.
Auto Loan Terms Explained
- APR vs. interest rate
- The interest rate is the cost of borrowing the principal, expressed per year. The APR (annual percentage rate) is intended to reflect the yearly cost of the loan, and in some jurisdictions it also includes certain lender fees. In this calculator the APR is converted to a monthly rate by dividing by 12.
- Principal / amount financed
- The amount actually borrowed: vehicle price minus down payment and trade-in value, plus any taxes, fees, or add-ons that are rolled into the loan.
- Down payment
- Cash paid upfront. It reduces the amount financed, and therefore both the monthly payment and total interest.
- Trade-in value
- The amount a dealer credits for your current vehicle. It works like a down payment, reducing the amount you need to borrow.
- Negative equity
- Owing more on a loan than the vehicle is worth (sometimes called being "upside down"). It can occur with small down payments, long terms, or when a balance from a previous loan is rolled into a new one.
- Loan term
- The number of months over which the loan is repaid, commonly 36 to 84 months.
- Amortization
- The process of paying off a loan through equal scheduled payments, each covering that month's interest first, with the remainder reducing the principal.
- Total cost of loan
- The sum of all payments: monthly payment × number of months. Subtracting the amount financed gives the total interest paid. Adding the down payment and trade-in gives the total outlay for the vehicle.
- Sales tax and fees
- Taxes, registration, documentation, and similar charges vary by location. If they are financed, they increase the principal and thus the interest; if they are paid upfront, they do not. Enter prices in this calculator accordingly.
Interpreting Your Result
Principal and interest split. Each monthly payment has two parts: interest on the current balance, and principal repayment. The interest portion for a month is the balance × the monthly rate \(r\). For example, on $25,000 at 6% APR over 60 months (payment $483.32), the first month's interest is \(25{,}000 \times 0.005 = \$125.00\), so about $358.32 goes to principal and the balance falls to about $24,641.68. In month 2 the interest is about $123.21, so slightly more goes to principal.
Why early payments are mostly interest. Interest is charged on the outstanding balance, which is highest at the start. As the balance declines, the interest portion shrinks and the principal portion grows, while the total payment stays constant. By the final payments, only a few dollars of each payment is interest.
Total interest, amount financed, and term. Total interest equals total paid minus the amount financed. For a fixed rate, it rises with both the amount financed and the term, because the balance stays outstanding longer. A lower payment from a longer term usually means more total interest, as the comparison table above shows.
Negative equity risk. Vehicles typically lose value fastest in their first years. With a long term, the loan balance falls slowly, especially early on when most of each payment is interest, so the balance can exceed the car's market value for a longer period. This matters if the car is sold, traded in, or totaled while the loan is outstanding. A larger down payment or a shorter term reduces this risk.
Limits of the estimate. The result is an estimate based on a fixed APR and equal monthly payments. It does not include insurance, fuel, maintenance, registration, or taxes and fees unless you include them in the price or amount financed. Lender calculations may differ slightly because of rounding, payment dates, or additional charges. This is general information, not financial advice.
Central bank policy rates today
The latest official policy rates of major central banks, updated automatically — the benchmark that bank deposit and loan rates follow.
- Federal Reserve · United States
- 3.75–4.00%
- As of
- 2026-11-12
- Change in 1 year
- 0 pp
Latest change Up +25 bp Federal Reserve changed its rate on 2026-09-17: from 3.50–3.75% to 3.75–4.00%.
| Central bank | Policy rate | As of | Change in 1 year |
|---|---|---|---|
| Banco Central do Brasil (Selic) · Brazil | 13.75% | 2026-11-16 | −1.25 pp |
| Banco de México · Mexico | 6.25% | 2026-11-10 | −1.00 pp |
| Federal Reserve · United States | 3.75–4.00% | 2026-11-12 | 0 pp |
| ECB | 2.50% | 2026-11-16 | +0.50 pp |
| Sveriges Riksbank · Sweden | 2.00% | 2026-11-16 | +0.25 pp |
| Saudi Central Bank (SAMA) · Saudi Arabia | 4.50% | 2026-10-29 | 0 pp |
| Reserve Bank of Australia · Australia | 4.60% | 2026-10-31 | +1.00 pp |
| Central Bank of the Republic of Türkiye · Türkiye | 36.00% | 2026-11-06 | −3.50 pp |
| Bank of Russia · Russia | 14.00% | 2026-11-10 | −2.50 pp |
| People’s Bank of China · China | 3.00% | 2026-11-10 | 0 pp |
| Bank of Canada · Canada | 2.50% | 2026-11-13 | +0.25 pp |
| Reserve Bank of India · India | 5.50% | 2026-10-19 | 0 pp |
| Bank of England · United Kingdom | 4.00% | 2026-11-16 | 0 pp |
| Bank of Japan · Japan | 1.25% | 2026-11-10 | +0.75 pp |
| Bank of Korea · South Korea | 3.00% | 2026-11-02 | +0.50 pp |
Federal Reserve: key rates and overnight market rates
The rates that frame monetary policy and the overnight market rate they steer, each with the date of its latest published value.
| Rate | Level | As of | Change in 1 year |
|---|---|---|---|
| Federal funds target range | 3.75–4.00% | 2026-11-13 | 0 pp |
| Effective federal funds rate (EFFR) | 3.88% | 2026-11-13 | 0 pp |
| Secured Overnight Financing Rate (SOFR) | 3.90% | 2026-11-13 | −0.10 pp |
Each rate keeps the date of its own latest published value; overnight market rates are published on the next business day.
Latest figure: 2026-11-12 Data last updated 2026-11-16 · current
Source: Banco Central do Brasil ODbL; Bank for International Settlements (BIS) Terms of permitted use of BIS statistics; Federal Reserve Bank of New York New York Fed Terms of Use; Board of Governors of the Federal Reserve System Public domain (U.S. government work); European Central Bank ECB reuse policy; Sveriges Riksbank Riksbank open data terms; The World Bank Group CC BY 4.0; Reserve Bank of Australia 2026 RBA copyright terms (Cash Rate); Bank of Canada Bank of Canada terms of use; Bank of England Open Government Licence v3.0
The one-year change is computed by CalculatorLib from these data. The EFFR and SOFR are subject to the Terms of Use posted at newyorkfed.org. The New York Fed is not responsible for publication of the EFFR and SOFR by CalculatorLib, does not sanction or endorse any particular republication, and has no liability for your use.
Source details and methodology
- Banco Central do Brasil
- Bank for International Settlements (BIS) — Central bank policy rates
- Federal Reserve Bank of New York — Reference rates (EFFR, SOFR)
- Board of Governors of the Federal Reserve System
- European Central Bank
- Sveriges Riksbank
- The World Bank Group — World Development Indicators (FR.INR.LEND, FR.INR.RINR)
- Reserve Bank of Australia 2026
- Bank of Canada
- Bank of England
FAQ
Does this include taxes and fees? No — enter the final financed price after taxes and fees if you want them rolled into the loan; otherwise the result reflects only the price you enter.
How does a bigger down payment help? It lowers the amount financed, which reduces both your monthly payment and the total interest you pay.
Is a shorter term better? A shorter term raises the monthly payment but lowers total interest, while a longer term does the opposite.