What is the SDLT Calculator?
This calculator estimates Stamp Duty Land Tax (SDLT) for residential property purchases in England and Northern Ireland. (Scotland uses LBTT and Wales uses LTT — this tool does not cover those.) Figures are based on the standard residential rate bands and the 5% surcharge for additional properties. SDLT rules change with government budgets, so always confirm current rates with HMRC before completing a purchase.
How to use it
Enter the agreed purchase price and choose your buyer type: a standard next-home purchase, a first-time buyer (who may qualify for relief), or an additional property such as a second home or buy-to-let (which attracts the surcharge). The calculator returns the total SDLT, the banded base tax, any surcharge, and your effective tax rate.
The formula explained
SDLT is progressive: you pay each band's rate only on the slice of the price within that band. The standard residential bands from 1 April 2025 are 0% up to £125,000, 2% from £125,001 to £250,000, 5% from £250,001 to £925,000, 10% from £925,001 to £1.5m, and 12% above £1.5m.
$$\text{SDLT} = \sum_i \left( \min(\text{Price},\, u_i) - l_i \right)^{+} \times r_i \quad\text{bands } (0\%,\,2\%,\,5\%,\,10\%,\,12\%)$$First-time buyers paying £500,000 or less pay 0% up to £300,000 and 5% on the rest. Above £500,000 the relief is lost and the standard bands apply to the whole price.
$$\text{SDLT} = 0.05 \times \left( \text{Price} - 300000 \right)^{+} \quad (\text{Price} \le 500000)$$An additional property bought for £40,000 or more pays the higher rates: 5 percentage points on every band, which is 5% of the whole price on top of the standard tax.
$$\text{SDLT} = \underbrace{\sum_i \left( \min(\text{Price},\, u_i) - l_i \right)^{+} \times r_i}_{\text{standard bands}} + 0.05 \times \text{Price}$$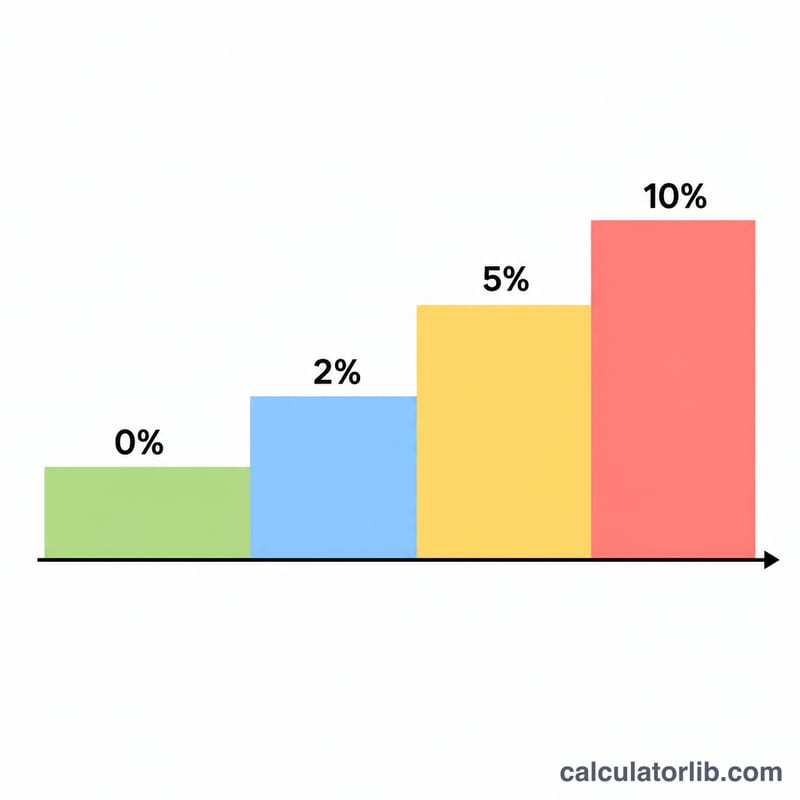
Worked example
For a £295,000 standard purchase (the gov.uk example): the first £125,000 is taxed at 0% (£0), the next £125,000 at 2% (£2,500), and the final £45,000 at 5% (£2,250). Total SDLT = £4,750, an effective rate of about 1.61%.
$$\text{SDLT} = 0 \times 125000 + 0.02 \times 125000 + 0.05 \times 45000 = 0 + 2500 + 2250 = 4750$$
FAQ
Does this cover Scotland or Wales? No. Scotland uses Land and Buildings Transaction Tax (LBTT) and Wales uses Land Transaction Tax (LTT), which have different bands.
When does the surcharge apply? The 5% surcharge generally applies when you buy an additional residential property (you already own one) such as a second home or a buy-to-let.
Is the result official? No — it's an estimate for guidance only. Reliefs, leasehold rules and recent rate changes may affect your actual bill; check with HMRC or a conveyancer.