Social Security PIA Calculator (US)

Social Security PIA Calculator (US)

Emerging AI Skill PRO

Enter Calculation

Selects the official SSA bend points. If disability or death comes first, use that year.
Cost-of-living increases are applied up to this year.

Formula

PIA=0.9min⁡(A,B1)+0.32max⁡(0,min⁡(A,B2)−B1)+0.15max⁡(0,A−B2)\text{PIA} = 0.9\,\min(A, B_1) + 0.32\,\max(0,\ \min(A, B_2) - B_1) + 0.15\,\max(0,\ A - B_2)
Usage stats

Advertisement

Results

Primary Insurance Amount (PIA)
$3,950.20
estimated monthly benefit at full retirement age
Year you turn 62 2027
First Bend Point $1,340
Second Bend Point $8,077
Tier 1 — 90% of first bend $1,206.00
Tier 2 — 32% to second bend $2,155.84
Tier 3 — 15% above second bend $588.45
Formula total before rounding $3,950.29
PIA in the eligibility year $3,950.20
Benefit year 2027

The PIA is rounded down to the next lower 10 cents, and again after each cost-of-living increase.

This is the PIA only. Claiming before or after full retirement age changes the monthly payment, which this tool does not compute. Your Social Security statement is the figure that counts.

Based on Cost-of-Living Increase and Other Determinations for 2027, 91 FR 67380 (Effective from 2027-01-01)

Report an error on this page

What the PIA is

The Primary Insurance Amount (PIA) is the monthly Social Security benefit a worker receives at full retirement age. It is the base figure for retirement, disability and survivor benefits. Claiming earlier lowers the monthly payment and claiming later raises it, so the PIA is often not the amount you are paid.

How the formula works

SSA applies three percentages to your Average Indexed Monthly Earnings (AIME): 90% up to the first bend point, 32% between the first and second bend points, and 15% above the second.

The bend points depend on the year you turn 62, not the year you claim. For 2027 they are $1,340 and $8,077. For 2026 they are $1,286 and $7,749.

Advertisement

Rounding and cost-of-living increases

SSA rounds the result down to the next lower 10 cents. It then applies each cost-of-living increase from the year you turn 62 onward, rounding down to 10 cents after each one. SSA's own example: an AIME of $5,825 for someone turning 62 in 2026 gives $2,609.88, which becomes a PIA of $2,609.80.

How to use this calculator

Enter your AIME and the year you turn 62. Choose a benefit year to include cost-of-living increases up to that year. You do not need to look up bend points, since the calculator selects the official ones for you. Use your disability or death year in place of the year you turn 62 if that comes first.

Advertisement

What it does not cover

It does not work out your AIME from an earnings history, and it does not apply early-claiming reductions, delayed retirement credits or family maximums. Workers first eligible before 1979 fall under different rules.
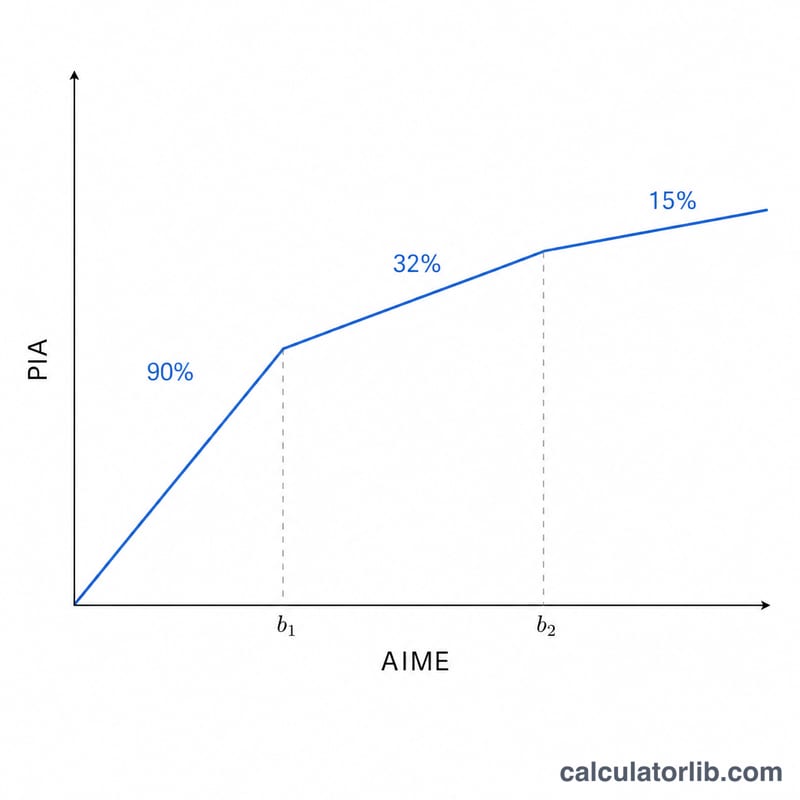

Piecewise line chart showing PIA versus AIME with three sloped segments at 90 percent, 32 percent, and 15 percent, separated by two vertical bend-point lines.
The PIA formula is a piecewise line: 90% up to the first bend point, 32% to the second, then 15%.

Sources & References

Last updated:

Most popular in Personal Finance

View all Personal Finance calculators