What Is the Marginal Propensity to Save?
The Marginal Propensity to Save (MPS) measures the proportion of an increase in income that a household or economy chooses to save rather than spend. It is a core concept in Keynesian economics and is used to understand consumption patterns, the spending multiplier, and how income shocks ripple through an economy.
How to Use This Calculator
Enter the change in savings (ΔSavings) and the change in income (ΔIncome) over the same period. The calculator divides the two to give the MPS, and also reports the Marginal Propensity to Consume (MPC), which is simply 1 − MPS. Both values are usually between 0 and 1.
The Formula Explained
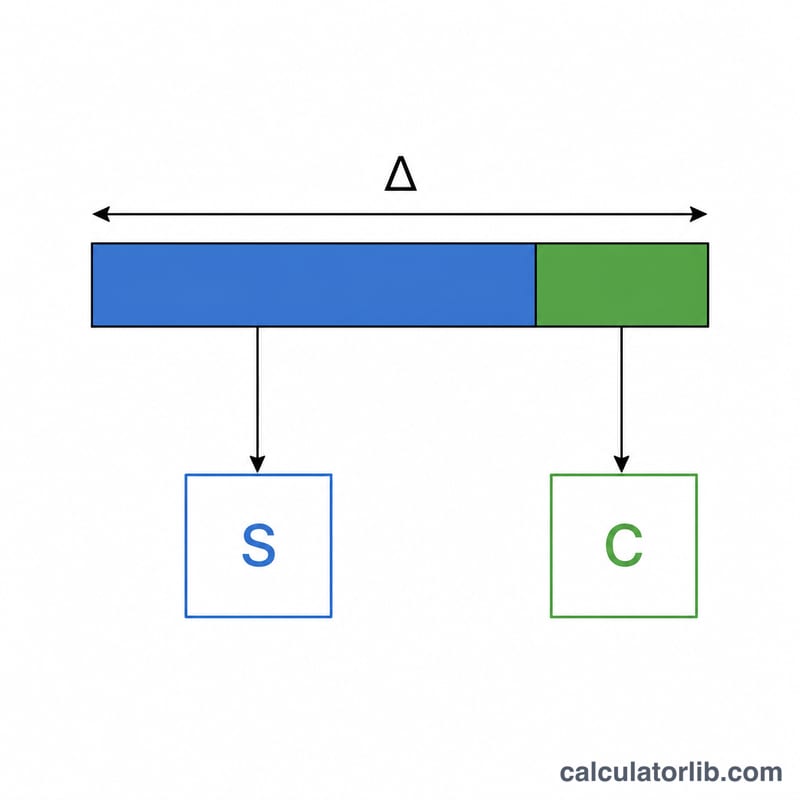
$$\text{MPS} = \frac{\Delta \text{Savings}}{\Delta \text{Income}}$$ Because any extra dollar of income is either saved or spent, \(\text{MPS} + \text{MPC} = 1\). So if households save 25 cents of every extra dollar, their MPS is 0.25 and their MPC is 0.75. A higher MPS means people save more of new income, which reduces the size of the fiscal multiplier.
Worked Example
Suppose a household's income rises by $1,000 and its savings increase by $200. Then $$\text{MPS} = \frac{200}{1{,}000} = 0.20.$$ This means 20% of the extra income is saved, while the remaining \(\text{MPC} = 1 - 0.20 = 0.80\) (80%) is consumed.
MPS and MPC Across Different Scenarios
The table keeps the change in income fixed at $1,000 and varies the change in savings. It uses \(\text{MPS} = \frac{\Delta S}{\Delta Y}\), \(\text{MPC} = 1 - \text{MPS}\) and the simple multiplier \(1/\text{MPS}\).
| ΔIncome | ΔSavings | MPS | MPC = 1 − MPS | Simple multiplier 1/MPS |
|---|---|---|---|---|
| $1,000 | $100 | 0.1 | 0.9 | 10 |
| $1,000 | $200 | 0.2 | 0.8 | 5 |
| $1,000 | $300 | 0.3 | 0.7 | 3.33 |
| $1,000 | $500 | 0.5 | 0.5 | 2 |
| $1,000 (edge case: savings fall) | −$50 | −0.05 | 1.05 | −20 (not meaningful) |
In the edge case, households saved less even though income rose, perhaps by drawing down savings or borrowing to spend. The result is a negative MPS and an MPC above 1. The simple multiplier formula does not give a sensible answer there. As MPS approaches 0, the multiplier grows very large. At exactly 0 it is undefined, because the formula divides by zero.
Interpreting Your MPS Result
- Low MPS (near 0): Most of an extra unit of income is spent. The MPC is high, and in the simple textbook model the spending multiplier \(1/\text{MPS}\) is large, so changes in spending ripple strongly through the economy.
- Mid-range MPS (about 0.2 to 0.5): Income is split between spending and saving. The simple multiplier is moderate, roughly 2 to 5.
- High MPS (near 1): Most extra income is saved. The MPC is low and the simple multiplier is close to 1, so extra income produces little additional spending.
In standard theory MPS lies between 0 and 1, because extra income is either spent or saved and MPS + MPC = 1. A negative MPS means savings fell while income rose. A value above 1 means savings rose by more than income, so spending fell. Both can reflect unusual circumstances such as debt repayment, a windfall, or one-off purchases. They can also point to data errors, mismatched time periods, or income and savings measured differently.
MPS is not a fixed constant. Estimates differ by income level, with lower-income households often spending a larger share of extra income, and they differ by country, time period, and whether the income change is seen as temporary or permanent. The simple multiplier also ignores taxes, imports, and other leakages, so real-world multipliers are usually smaller. This is general economic information, not personal financial advice.
Key Terms and Definitions
- ΔSavings (change in savings)
- The change in the amount saved between two periods or situations, \(\Delta S\).
- ΔIncome (change in income)
- The change in income (disposable income in most textbook treatments) over the same comparison, \(\Delta Y\).
- Marginal propensity to save (MPS)
- The fraction of an additional unit of income that is saved: \(\text{MPS} = \Delta S / \Delta Y\).
- Marginal propensity to consume (MPC)
- The fraction of an additional unit of income that is spent on consumption: \(\text{MPC} = \Delta C / \Delta Y\).
- Identity: MPS + MPC = 1
- Because additional income is either consumed or saved, \(\text{MPS} + \text{MPC} = 1\), so \(\text{MPC} = 1 - \text{MPS}\).
- Spending multiplier
- In the simple model without taxes or imports, \(k = \frac{1}{1 - \text{MPC}} = \frac{1}{\text{MPS}}\). It shows how much total output changes per unit change in autonomous spending.
- Average propensity to save (APS)
- The share of total income that is saved, \(\text{APS} = S / Y\). It differs from MPS, which looks only at the additional income.
- Keynesian consumption function
- The relationship \(C = a + bY\), where \(a\) is autonomous consumption (spending when income is zero) and \(b\) is the MPC. The matching savings function is \(S = -a + (1 - b)Y\), whose slope is the MPS.
FAQ
Can MPS be greater than 1? Normally no — you cannot save more than your additional income. A value above 1 usually signals a data error or that consumption fell.
What is the relationship between MPS and the multiplier? The simple spending multiplier equals \(1 \div \text{MPS}\). A lower MPS produces a larger multiplier.
Is MPS the same as the savings rate? No. The savings rate is total savings divided by total income; MPS measures only the change in savings relative to the change in income.