What is the Car Affordability Calculator?
This calculator works backwards from your budget: instead of starting with a car price, you tell it the monthly payment you can comfortably afford, and it tells you the total vehicle price that payment supports. It combines your down payment with the present value of your future monthly payments, discounted at your loan's interest rate.
How to use it
Enter the monthly payment you can afford, your down payment (cash plus trade-in value), the annual interest rate (APR) your lender offers, and the loan term in months. The result shows the maximum car price, the amount you would finance, the total you would pay, and the total interest cost.
The formula explained
The financed loan amount equals the present value of an annuity: \(P \times \frac{1 - (1+r)^{-n}}{r}\), where \(P\) is the monthly payment, \(r\) is the monthly rate (APR ÷ 12 ÷ 100) and \(n\) is the number of months. Adding your down payment gives the affordable price. If the rate is 0%, the financed amount is simply payment × months.
$$\text{Price} = \text{Down} + M \cdot \frac{1 - (1+r)^{-n}}{r}$$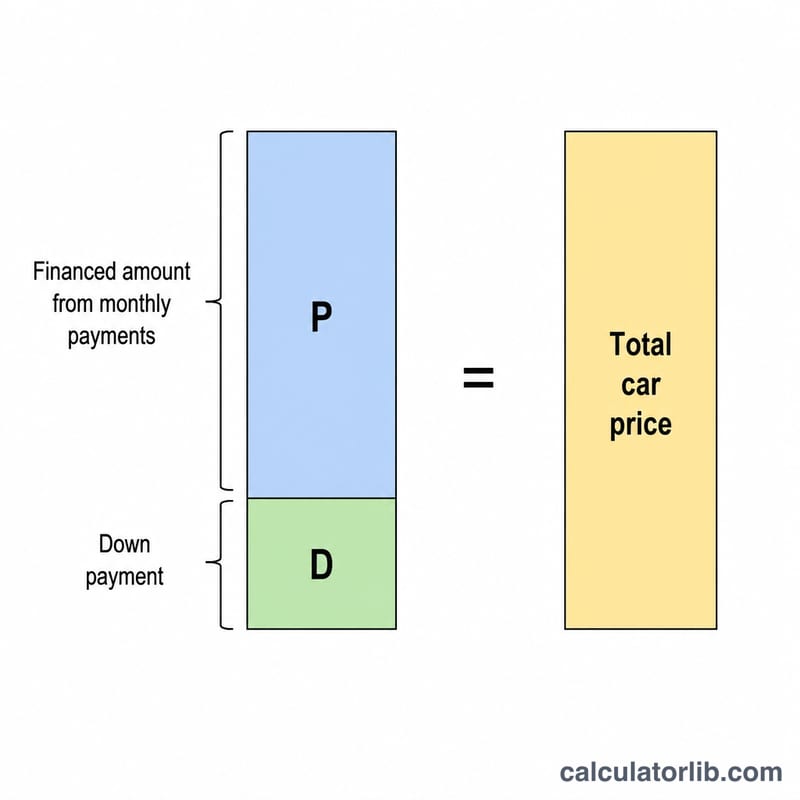
Worked example
Suppose you can pay $400/month for 60 months at 6% APR with $3,000 down. The monthly rate is 0.005. The factor \(\frac{1 - 1.005^{-60}}{0.005} \approx 51.7256\), so the financed amount ≈ $20,690.24. Adding $3,000 down gives an affordable price of about $23,690.24. Total paid is \(\$3{,}000 + \$24{,}000 = \$27{,}000\), so total interest ≈ $3,309.76.
How Loan Term and APR Change Affordable Price
This table holds the monthly payment fixed at $400 and the down payment at $3,000. It changes only the term and APR. Each financed amount comes from the annuity formula \(P = M \cdot \frac{1-(1+r)^{-n}}{r}\) with \(r = \text{APR}/1200\). Affordable price = financed amount + $3,000 down. Total interest = \(M \cdot n\) − financed amount. Sales tax, fees and trade-in are ignored, and figures are rounded to the nearest dollar.
| Term (months) | APR | Financed amount | Affordable price | Total interest |
|---|---|---|---|---|
| 36 | 4% | $13,548 | $16,548 | $852 |
| 48 | 4% | $17,716 | $20,716 | $1,484 |
| 60 | 4% | $21,720 | $24,720 | $2,280 |
| 72 | 4% | $25,567 | $28,567 | $3,233 |
| 84 | 4% | $29,264 | $32,264 | $4,336 |
| 36 | 6% | $13,148 | $16,148 | $1,252 |
| 48 | 6% | $17,032 | $20,032 | $2,168 |
| 60 | 6% | $20,690 | $23,690 | $3,310 |
| 72 | 6% | $24,136 | $27,136 | $4,664 |
| 84 | 6% | $27,381 | $30,381 | $6,219 |
| 36 | 8% | $12,765 | $15,765 | $1,635 |
| 48 | 8% | $16,385 | $19,385 | $2,815 |
| 60 | 8% | $19,727 | $22,727 | $4,273 |
| 72 | 8% | $22,814 | $25,814 | $5,986 |
| 84 | 8% | $25,664 | $28,664 | $7,936 |
Example substitution (6%, 60 months): \(r = 0.005\), \(n = 60\), so the factor is \(\frac{1-1.005^{-60}}{0.005} \approx 51.7256\). Then \(P \approx 400 \times 51.7256 = \$20,690\), and the price is $20,690 + $3,000 = $23,690.
Stretching the term from 36 to 84 months at 6% raises the affordable price by about $14,200. It also raises total interest from about $1,252 to $6,219. A longer term increases the sticker price you can reach, but the extra cost is interest.
Common Car Budget Guidelines
The rules below are rules of thumb (heuristics) that appear in US consumer-finance sources. They are general guidelines, not advice, and they are not tailored to any person's situation. Many households use different limits depending on income, other debts and local costs.
| Guideline | What it suggests |
|---|---|
| 20/4/10 rule | Put at least 20% down, finance for no more than 4 years (48 months), and keep total transportation costs (payment, insurance, fuel, maintenance) under about 10% of gross income. |
| Payment as a share of take-home pay | Keep the car payment, or in some versions total car spending, within roughly 15%–20% of monthly take-home (after-tax) pay. |
Typical loan terms in the US market are 60–72 months, which is longer than the 4-year limit in the 20/4/10 rule. The table in the previous section shows that longer terms raise the price a given payment reaches, but they also raise total interest. They can also leave a borrower owing more than the car is worth early in the loan.
Use these figures as reference points to compare against your own results. Insurance, fuel, registration and maintenance are not part of the loan payment, so they are worth including in any budget. This is general information, not financial advice.
Key Terms: APR, Principal, Down Payment, and More
- APR (annual percentage rate)
- The yearly cost of borrowing, shown as a percentage. It is entered as the rate field and converted to a monthly rate with \(r = \text{APR}/1200\).
- Monthly rate (\(r\))
- The interest rate applied each month. For example, 6% APR gives \(r = 0.005\).
- Loan term (\(n\))
- The number of monthly payments, e.g. 60 for a five-year loan. It is the exponent in \((1+r)^{-n}\).
- Principal / financed amount (\(P\))
- The amount actually borrowed. The calculator finds it as \(M \cdot \frac{1-(1+r)^{-n}}{r}\), where \(M\) is the monthly payment.
- Down payment
- Cash paid upfront. It is added to the financed amount to give the affordable price and reduces what you borrow.
- Trade-in equity
- The trade-in value of your current car minus any loan still owed on it. Positive equity can be added to the down payment. Negative equity is usually rolled into the new loan and increases \(P\).
- Total interest
- The cost of borrowing: \(M \cdot n - P\), the sum of all payments minus the principal.
- Out-the-door price
- The full amount due at purchase, including the vehicle price, taxes, title and registration, and dealer fees. Compare it with the calculator's affordable price, since taxes and fees must come from the down payment or the loan.
FAQ
Does this include taxes and fees? No — the result is the vehicle price your payment supports. Budget separately for sales tax, registration, and dealer fees.
What APR should I use? Use the rate you have actually been quoted. Rates vary by credit score, loan term and whether the car is new or used.
Should I include my trade-in? Yes, add the trade-in value to your cash down payment for a more accurate price ceiling.