What This Calculator Does
Applies to the United States (IRS federal taxes). When you file your federal income tax return after the deadline and still owe tax, the IRS charges two separate penalties plus interest. This calculator estimates the Failure-to-File penalty, the Failure-to-Pay penalty, accrued interest, and your total amount due. Figures are estimates based on standard IRS rules; your actual notice may differ and interest rates change quarterly.
How to Use It
Enter the amount of unpaid tax you owe, the number of months your return is late (the IRS counts any part of a month as a full month, so round up), and the current annual IRS interest rate (commonly 8% in recent years — check the IRS website for the rate that applies to your period). The calculator returns each penalty separately and combines them into a total.
The Formula Explained
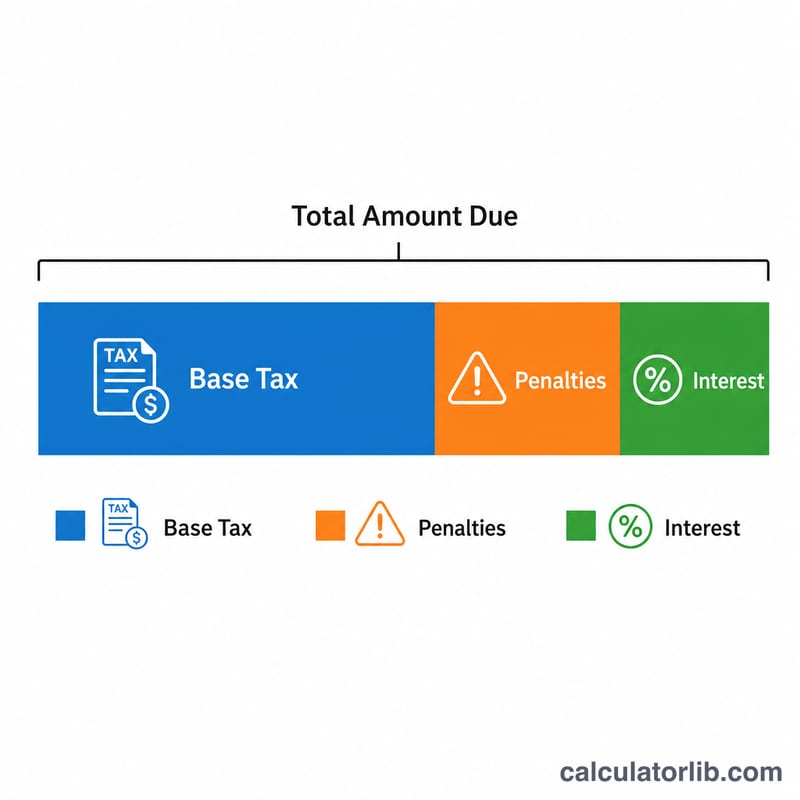
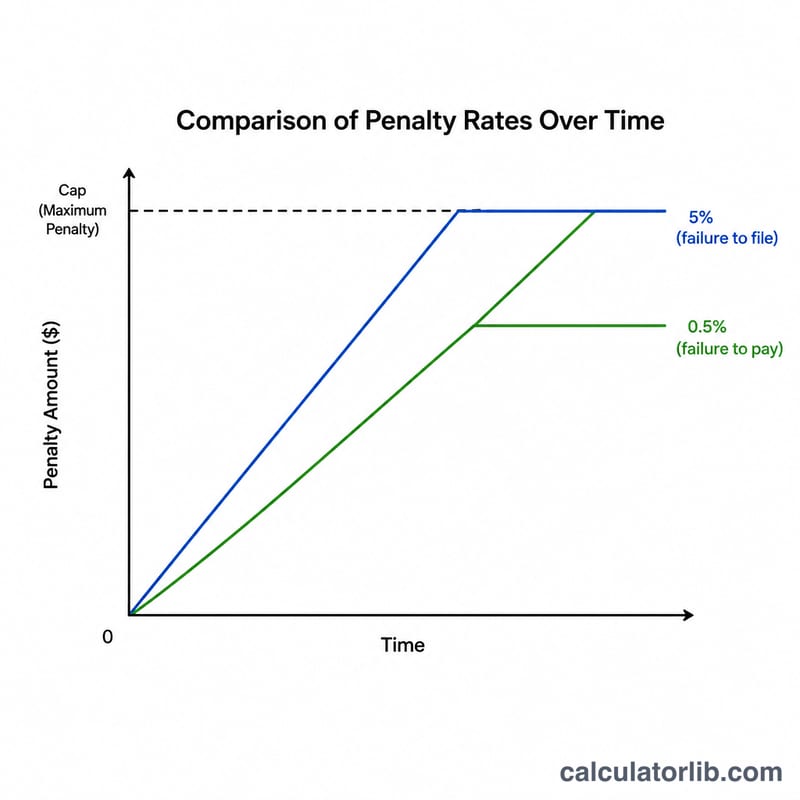
The Failure-to-File penalty is 5% of unpaid tax per month, capped at 25% total. The Failure-to-Pay penalty is 0.5% of unpaid tax per month, also capped at 25%. Because both can apply in the same month, the IRS reduces the Failure-to-File penalty by the Failure-to-Pay penalty for any overlapping month. Interest is charged on the unpaid balance and is approximated here as simple interest: \(\text{Tax} \times \text{rate} \times (\text{months} \div 12)\).
$$\text{Total} = T + \min(0.25,\,0.05\,m)\,T + \text{Interest}$$
$$\text{where}\quad \left\{ \begin{aligned} T &= \text{Tax Owed} \\ m &= \text{Months Late} \\ \text{FTP} &= \min(0.25\,T,\ 0.005\,m\,T) \\ \text{FTF} &= \min(0.25\,T,\ 0.05\,m\,T) - \text{FTP} \\ \text{Interest} &= T \cdot \dfrac{\text{Rate (\%)}}{100} \cdot \dfrac{m}{12} \end{aligned} \right.$$
Worked Example
Suppose you owe $5,000 and are 3 months late, with an 8% annual interest rate. Failure-to-File:
$$5\% \times \$5{,}000 \times 3 = \$750$$
Failure-to-Pay:
$$0.5\% \times \$5{,}000 \times 3 = \$75$$
The combined Failure-to-File is reduced by the Failure-to-Pay:
$$\$750 - \$75 = \$675$$
Total penalties:
$$\$675 + \$75 = \$750$$
Interest:
$$\$5{,}000 \times 0.08 \times (3 \div 12) = \$100$$
Total due:
$$\$5{,}000 + \$750 + \$100 = \$5{,}850$$
Key Terms and Definitions
- Failure-to-File penalty: a US IRS penalty for not filing a return by the due date (including extensions). It is generally 5% of the unpaid tax for each month or part of a month the return is late, up to a maximum of 25%. It is reduced to 4.5% per month in months when the Failure-to-Pay penalty also applies.
- Failure-to-Pay penalty: a penalty of generally 0.5% of the unpaid tax for each month or part of a month the tax remains unpaid after the due date, up to a maximum of 25%.
- Unpaid tax: the tax due on the return after subtracting withholding, estimated payments, and credits. Penalties are based on this amount, not on total income or total tax.
- Months late: the number of months since the due date. Any part of a month counts as a full month, so 1 day late and 29 days late both count as 1 month.
- IRS underpayment interest rate: the federal short-term rate plus 3 percentage points. The IRS sets it quarterly, so it can change during the period you owe.
- Simple vs. compounded interest: simple interest is charged only on the original unpaid tax. Compounded interest is also charged on previously accrued interest. The IRS compounds daily, so actual interest is slightly higher than a simple estimate. This calculator uses simple interest.
- Penalty cap of 25%: the maximum for each of the two penalties under IRS rules. The calculator also limits the combined penalty to 25% of the tax owed.
Interpreting Your Result
This calculator applies to US federal income tax under IRS rules. It does not apply to other countries or to state taxes.
- Penalties and interest are separate. Penalties are a percentage of the unpaid tax. Interest is a charge for the time the money was owed, so it grows the longer the balance stays unpaid.
- Overlap of FTF and FTP. In months when both penalties apply, the FTF penalty is reduced by the FTP penalty. The combined rate is therefore 5% per month. Over the first 5 months, FTF nets to 22.5% and FTP is 2.5%, for a combined 25%. FTP can continue to accrue afterward, up to its own 25% cap at 50 months.
- Minimum FTF penalty. If a return is more than 60 days late, the minimum FTF penalty is the lesser of a fixed dollar amount or 100% of the tax owed. For returns due in 2024 the amount is $450; the IRS adjusts it annually. This calculator does not apply that minimum, so a small balance could carry a higher actual penalty.
- Interest is approximate. The IRS compounds interest daily at a rate that changes quarterly. Your actual interest may be slightly higher than the simple-interest estimate shown.
- Penalties are based on tax still owed. The base is the tax due after payments and credits. Entering the full tax liability instead of the remaining balance will overstate the result.
- Relief may be available. Under IRS rules, penalties may be reduced or removed through first-time penalty abatement (generally for taxpayers with a clean recent compliance history) or reasonable cause. Interest generally continues to accrue on any unpaid tax, and on penalties that remain.
This tool provides general, informational estimates only and is not tax advice. For your exact balance, check your IRS notice or account, or consult a qualified tax professional.
Central bank policy rates today
The latest official policy rates of major central banks, updated automatically — the benchmark that bank deposit and loan rates follow.
- Federal Reserve · United States
- 3.75–4.00%
- As of
- 2026-11-13
- Change in 1 year
- 0 pp
Latest change Up +25 bp Federal Reserve changed its rate on 2026-09-17: from 3.50–3.75% to 3.75–4.00%.
| Central bank | Policy rate | As of | Change in 1 year |
|---|---|---|---|
| Banco Central do Brasil (Selic) · Brazil | 13.75% | 2026-11-16 | −1.25 pp |
| Banco de México · Mexico | 6.25% | 2026-11-10 | −1.00 pp |
| Federal Reserve · United States | 3.75–4.00% | 2026-11-13 | 0 pp |
| ECB | 2.50% | 2026-11-17 | +0.50 pp |
| Sveriges Riksbank · Sweden | 2.00% | 2026-11-17 | +0.25 pp |
| Saudi Central Bank (SAMA) · Saudi Arabia | 4.50% | 2026-10-29 | 0 pp |
| Reserve Bank of Australia · Australia | 4.60% | 2026-10-31 | +1.00 pp |
| Central Bank of the Republic of Türkiye · Türkiye | 36.00% | 2026-11-06 | −3.50 pp |
| Bank of Russia · Russia | 14.00% | 2026-11-10 | −2.50 pp |
| People’s Bank of China · China | 3.00% | 2026-11-10 | 0 pp |
| Bank of Canada · Canada | 2.50% | 2026-11-13 | +0.25 pp |
| Reserve Bank of India · India | 5.50% | 2026-10-19 | 0 pp |
| Bank of England · United Kingdom | 4.00% | 2026-11-17 | 0 pp |
| Bank of Japan · Japan | 1.25% | 2026-11-10 | +0.75 pp |
| Bank of Korea · South Korea | 3.00% | 2026-11-02 | +0.50 pp |
Federal Reserve: key rates and overnight market rates
The rates that frame monetary policy and the overnight market rate they steer, each with the date of its latest published value.
| Rate | Level | As of | Change in 1 year |
|---|---|---|---|
| Federal funds target range | 3.75–4.00% | 2026-11-13 | 0 pp |
| Effective federal funds rate (EFFR) | 3.88% | 2026-11-13 | 0 pp |
| Secured Overnight Financing Rate (SOFR) | 3.90% | 2026-11-13 | −0.10 pp |
Each rate keeps the date of its own latest published value; overnight market rates are published on the next business day.
Latest figure: 2026-11-13 Data last updated 2026-11-17 · current
Source: Banco Central do Brasil ODbL; Bank for International Settlements (BIS) Terms of permitted use of BIS statistics; Federal Reserve Bank of New York New York Fed Terms of Use; Board of Governors of the Federal Reserve System Public domain (U.S. government work); European Central Bank ECB reuse policy; Sveriges Riksbank Riksbank open data terms; The World Bank Group CC BY 4.0; Reserve Bank of Australia 2026 RBA copyright terms (Cash Rate); Bank of Canada Bank of Canada terms of use; Bank of England Open Government Licence v3.0
The one-year change is computed by CalculatorLib from these data. The EFFR and SOFR are subject to the Terms of Use posted at newyorkfed.org. The New York Fed is not responsible for publication of the EFFR and SOFR by CalculatorLib, does not sanction or endorse any particular republication, and has no liability for your use.
Source details and methodology
- Banco Central do Brasil
- Bank for International Settlements (BIS) — Central bank policy rates
- Federal Reserve Bank of New York — Reference rates (EFFR, SOFR)
- Board of Governors of the Federal Reserve System
- European Central Bank
- Sveriges Riksbank
- The World Bank Group — World Development Indicators (FR.INR.LEND, FR.INR.RINR)
- Reserve Bank of Australia 2026
- Bank of Canada
- Bank of England
FAQ
Are penalties really stacked? Yes, but the law caps the combined effect — the file penalty is reduced by the pay penalty in months they overlap, so the combined monthly rate is effectively 5%.
Is there a maximum? Each penalty maxes out at 25% of the unpaid tax. Interest, however, continues to accrue until the balance is paid in full.
Can penalties be removed? The IRS may grant first-time penalty abatement or relief for reasonable cause. This tool does not account for waivers.