What is the BIS Capital Adequacy Ratio?
The BIS capital adequacy ratio (CAR), defined under the Basel framework of the Bank for International Settlements, measures how much regulatory capital a bank holds relative to its risk-weighted assets (RWA). It is a core solvency indicator: a higher ratio means a bank can absorb more losses before becoming insolvent. Regulators typically require a minimum total CAR of 8%.
The formula
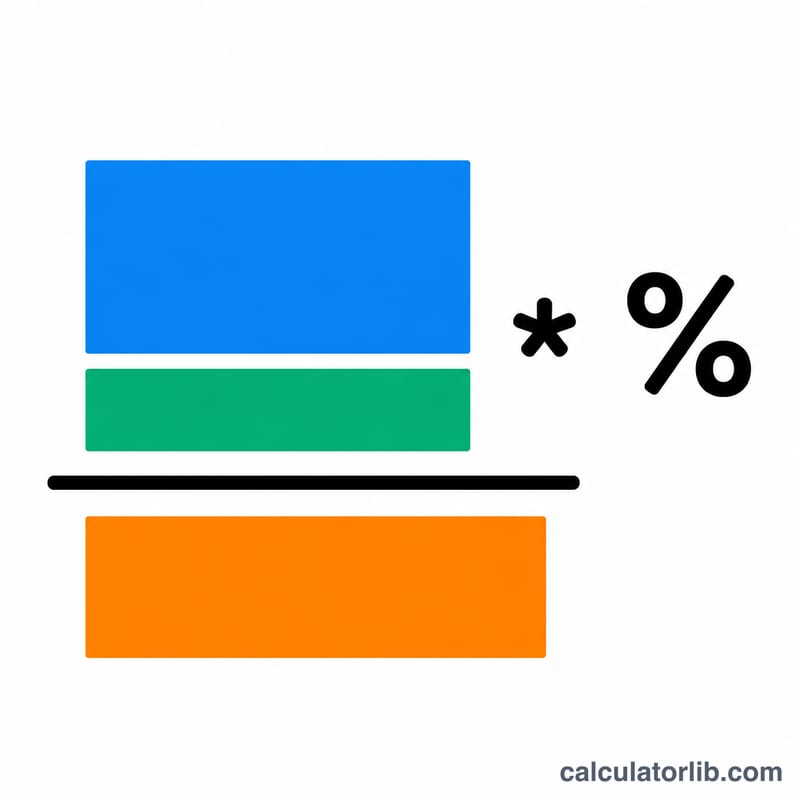
The ratio adds Tier 1 (core) capital and Tier 2 (supplementary) capital, then divides by risk-weighted assets:
$$\text{CAR} = \frac{\text{Tier 1} + \text{Tier 2}}{\text{RWA}} \times 100\%$$Here \(\text{Tier 1}\) is core capital such as common equity and retained earnings, \(\text{Tier 2}\) is supplementary capital such as subordinated debt and certain reserves, and \(\text{RWA}\) is total assets each weighted by its credit, market, and operational risk.
How to use this calculator
Enter the bank's Tier 1 capital, Tier 2 capital, and total risk-weighted assets in the same currency units (for example, millions). The calculator returns the total CAR, the total capital figure, and the Tier 1 capital ratio so you can compare each against regulatory minimums.
Worked example
Suppose a bank has \(\text{Tier 1}=50\), \(\text{Tier 2}=30\), and \(\text{RWA}=1000\) (millions). Total capital is \(50+30=80\), so:
$$\text{CAR} = \frac{50 + 30}{1000} \times 100\% = 8.00\%$$The Tier 1 ratio is \(\frac{50}{1000}\times 100\% = 5.00\%\). The bank exactly meets the 8% total minimum.
Basel III Minimum Capital Requirements and Buffers
The capital adequacy ratio (CAR) is measured against the minimum standards set by the Basel III framework, which is issued by the Basel Committee on Banking Supervision (BCBS) at the Bank for International Settlements (BIS). All figures below are expressed as a percentage of risk-weighted assets (RWA). These are the internationally agreed minimums; national regulators (for example, the EU, the UK PRA, or the US federal banking agencies) implement them in local law and may set higher requirements, so the exact thresholds a specific bank must meet depend on its home jurisdiction.
| Requirement | Level (% of RWA) | Source |
|---|---|---|
| Common Equity Tier 1 (CET1) minimum | 4.5% | Basel III / BCBS |
| Tier 1 capital minimum | 6.0% | Basel III / BCBS |
| Total capital minimum (Tier 1 + Tier 2) | 8.0% | Basel III / BCBS |
| Capital conservation buffer (CET1) | 2.5% | Basel III / BCBS |
| Countercyclical buffer (CET1, jurisdiction-set) | 0% – 2.5% | Basel III / BCBS (set by national authorities) |
| G-SIB / systemically important surcharge (CET1) | 1.0% – 3.5% (bucket-dependent) | BCBS G-SIB framework / FSB |
| Effective total capital requirement (8% minimum + 2.5% conservation buffer) | 10.5% | Basel III / BCBS |
The 8% total minimum is the hard floor. Adding the 2.5% capital conservation buffer gives an effective total requirement of 10.5% of RWA. Where a countercyclical buffer (up to 2.5%) or a G-SIB surcharge (1.0%–3.5% depending on the assigned bucket) applies, those amounts — which must be met with CET1 capital — are added on top, so the largest global banks face materially higher effective requirements.
FAQ
What is a good CAR? Basel III sets a minimum total capital ratio of 8%, but many regulators add buffers, so well-capitalized banks often report 12% or more.
What is the difference between Tier 1 and Tier 2? Tier 1 is high-quality core capital available to absorb losses on a going-concern basis; Tier 2 is lower-quality supplementary capital used mainly in wind-down scenarios.
Why use risk-weighted assets instead of total assets? RWA scales each exposure by its riskiness, so safer assets require less capital backing than riskier ones.