What This Calculator Does
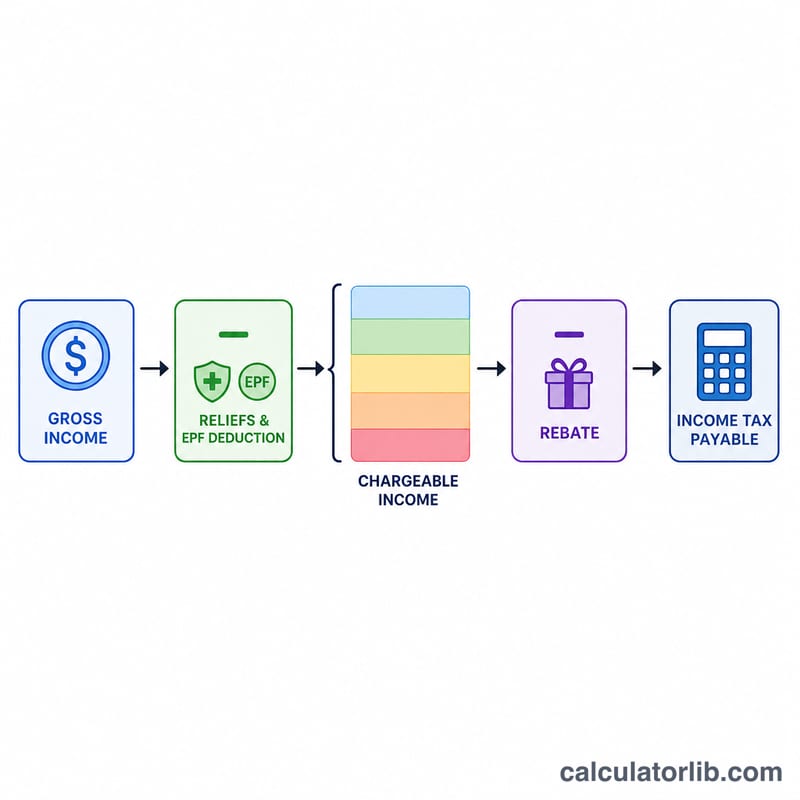
This tool estimates personal income tax for Malaysian tax residents for the Year of Assessment 2024 (YA2024), administered by LHDN (Inland Revenue Board). It applies the resident progressive tax bands, subtracts your personal reliefs, and applies the RM400 rebate available when chargeable income does not exceed RM35,000. It assumes you are a tax resident; non-residents are taxed at a flat 30% and are out of scope.
How to Use It
Enter your total annual income, your EPF or approved-fund contributions (relief capped at RM4,000), any other reliefs you qualify for (lifestyle, medical, education, etc.), and your marital status. The default RM9,000 individual relief is applied automatically, plus RM4,000 if you support a spouse with no income.
The Formula Explained
First, chargeable income = annual income − total reliefs. Then the YA2024 resident bands are applied progressively: 0% up to RM5,000; 1% on the next RM15,000; 3% next RM15,000; 6% next RM15,000; 11% next RM20,000; 19% next RM30,000; 25% next RM300,000; 26%, 28% and 30% on higher bands. Finally a RM400 rebate (RM800 if married) is deducted when chargeable income ≤ RM35,000.
$$\text{Tax Payable} = \operatorname{Progressive}(C) - \text{Rebate}$$
$$\text{where}\quad \left\{ \begin{aligned} C &= \text{Income} - 9000 - \min\!\left(\text{EPF},\,4000\right) - \text{Reliefs} \\ \text{Rebate} &= 400 \;\text{ if } C \le 35000 \end{aligned} \right.$$
Worked Example
A single taxpayer earns RM60,000 with RM4,000 EPF. Reliefs = RM9,000 + RM4,000 = RM13,000, so chargeable income = RM47,000. Tax = 0 + (15,000×1%) + (15,000×3%) + (12,000×6%) = 150 + 450 + 720 = RM1,320. Chargeable income exceeds RM35,000, so no rebate applies — tax payable is RM1,320.
$$\text{Reliefs} = 9000 + 4000 = 13000$$
$$\text{Chargeable income} = 60000 - 13000 = 47000$$
$$\text{Tax} = 0 + (15000 \times 1\%) + (15000 \times 3\%) + (12000 \times 6\%) = 150 + 450 + 720 = 1320$$
YA2024 Resident Tax Rate Table
These are the progressive income tax rates for Malaysian tax residents for the Year of Assessment (YA) 2024, as administered by LHDN. They apply to chargeable income (income after reliefs), in Malaysian ringgit (RM). Non-residents are taxed under different rules and are not covered here.
| Chargeable income band (RM) | Rate | Tax on the band (RM) | Cumulative tax at band's upper limit (RM) |
|---|---|---|---|
| 0 – 5,000 | 0% | 0 | 0 |
| 5,001 – 20,000 | 1% | 150 | 150 |
| 20,001 – 35,000 | 3% | 450 | 600 |
| 35,001 – 50,000 | 6% | 900 | 1,500 |
| 50,001 – 70,000 | 11% | 2,200 | 3,700 |
| 70,001 – 100,000 | 19% | 5,700 | 9,400 |
| 100,001 – 400,000 | 25% | 75,000 | 84,400 |
| 400,001 – 600,000 | 26% | 52,000 | 136,400 |
| 600,001 – 2,000,000 | 28% | 392,000 | 528,400 |
| Above 2,000,000 | 30% | 30% of the excess over 2,000,000 | 528,400 + 30% of the excess |
To find tax for a given chargeable income, take the cumulative tax at the top of the previous band and add the band rate times the amount above that band's lower threshold. A resident individual whose chargeable income is RM35,000 or less also receives a RM400 rebate, which is deducted from the tax calculated.
Tax Payable at Different Income Levels
Assumptions: a single Malaysian resident with the RM9,000 individual relief and RM4,000 EPF relief (total RM13,000), and no other reliefs. Chargeable income = gross income − 13,000. The RM400 rebate applies only where chargeable income is RM35,000 or less. All figures are in RM and use the YA2024 resident rates.
| Gross income | Chargeable income | Tax before rebate | Rebate | Tax payable | Effective rate (tax ÷ gross) |
|---|---|---|---|---|---|
| 40,000 | 27,000 | 360 | 400 | 0 | 0.00% |
| 60,000 | 47,000 | 1,320 | 0 | 1,320 | 2.20% |
| 100,000 | 87,000 | 6,930 | 0 | 6,930 | 6.93% |
| 200,000 | 187,000 | 31,150 | 0 | 31,150 | 15.58% |
How each row is computed
- RM40,000: chargeable income 40,000 − 13,000 = 27,000. Tax = 150 + (27,000 − 20,000) × 3% = 150 + 210 = 360. Rebate of 400 applies because 27,000 ≤ 35,000, so tax payable is 0 (the rebate cannot create a refund through this calculation).
- RM60,000: chargeable income 47,000. Tax = 600 + (47,000 − 35,000) × 6% = 600 + 720 = 1,320. No rebate.
- RM100,000: chargeable income 87,000. Tax = 3,700 + (87,000 − 70,000) × 19% = 3,700 + 3,230 = 6,930.
- RM200,000: chargeable income 187,000. Tax = 9,400 + (187,000 − 100,000) × 25% = 9,400 + 21,750 = 31,150. Effective rate = 31,150 ÷ 200,000 = 15.575%, shown as 15.58%.
Real results will differ if you claim additional reliefs (for example lifestyle, medical, education, or spouse and child reliefs) or have a different EPF contribution. Enter those in the calculator's reliefs field.
Key Terms: Chargeable Income, Relief and Rebate
- Tax resident
- For Malaysian income tax, an individual is generally a resident for a year if they are in Malaysia for 182 days or more in the calendar year (other tests also exist for shorter stays that link to adjacent years). Residents are taxed at the progressive rates and can claim reliefs and rebates.
- Year of Assessment (YA)
- The tax year in which income is assessed. For individuals, YA2024 covers income earned in the calendar year 1 January to 31 December 2024, with the return filed in 2025.
- Gross (total) income
- Income from all taxable sources, such as employment, business, rent, and interest, before any reliefs are deducted. Exempt income is excluded.
- Relief
- A fixed or capped amount deducted from your total income to arrive at chargeable income. Examples are the RM9,000 individual relief and the EPF relief. Reliefs reduce the income that is taxed.
- Chargeable income
- Total income minus reliefs and allowable deductions. This is the amount to which the progressive rate table is applied. In this calculator: income − 9,000 − min(EPF, 4,000) − other reliefs.
- Rebate vs relief
- A relief lowers the income that is taxed, so its value depends on your tax rate. A rebate is subtracted directly from the tax calculated, ringgit for ringgit. The RM400 rebate applies when chargeable income is RM35,000 or less.
- EPF relief
- A relief for mandatory contributions to the Employees Provident Fund (and approved schemes), limited to RM4,000 in this calculator for YA2024. Contributions above that cap do not give extra relief here.
- Progressive tax
- A system in which higher slices of income are taxed at higher rates. Each rate applies only to the part of chargeable income that falls within its band, not to all of it.
- Effective vs marginal rate
- The marginal rate is the rate on your next ringgit of chargeable income (the top band you reach). The effective rate is total tax payable divided by income (here gross income), which is always lower than the marginal rate for a progressive system.
- LHDN
- Lembaga Hasil Dalam Negeri, the Inland Revenue Board of Malaysia, the authority that administers and collects income tax. Official rules and filing information are on its website.
This calculator gives a general estimate for YA2024 only and is not professional tax advice. Check your own situation with LHDN or a qualified tax adviser.
Income and jobs: Malaysia
Average income and unemployment in Malaysia compared with the world, from the World Bank: a benchmark for the figures you enter above.
- GNI per capita 2025
- 12,380 USD
- GDP per capita, PPP 2025
- 41,498 intl. $
- World: 25,704
- Unemployment 2025
- 3.8%
- World: 4.8%
Latest change Up +6.3% 2025: 12,380 USD, against 11,650 USD in 2024. CalculatorLib computes this change from the two published figures.
In 2025, gross national income per person in Malaysia was 12,380 US dollars a year, about 1,032 US dollars a month. World: 14,244 USD
| Year | GNI per capita (USD) | GDP per capita, PPP (intl. $) | Unemployment |
|---|---|---|---|
| 2025 | 12,380 | 41,498 | 3.8% |
| 2024 | 11,650 | 38,836 | 3.8% |
| 2023 | 11,700 | 36,497 | 3.9% |
| 2022 | 11,620 | 34,414 | 3.9% |
| 2021 | 10,520 | 29,823 | 4.6% |
| 2020 | 10,110 | 27,475 | 4.5% |
| 2019 | 10,750 | 28,934 | 3.3% |
| 2018 | 10,200 | 27,794 | 3.3% |
| 2017 | 9,560 | 26,416 | 3.4% |
| 2016 | 9,800 | 25,286 | 3.4% |
GNI per capita (Atlas method) is the average of all income in the economy, not a typical salary; PPP dollars adjust for local prices.
Malaysia and other countries
GNI per capita in current US dollars (Atlas method) — each country’s latest published year.
- United States 88,810 USD (2025)
- France 48,630 USD (2025)
- Japan 38,340 USD (2025)
- South Korea 37,880 USD (2025)
- Saudi Arabia 36,070 USD (2025)
- Türkiye 16,300 USD (2025)
- Russia 15,960 USD (2025)
- World 14,244 USD (2025)
- China 14,230 USD (2025)
- Mexico 13,730 USD (2025)
- Malaysia 12,380 USD (2025)
- Vietnam 4,970 USD (2025)
- India 2,760 USD (2025)
Years can differ between rows: each figure is shown with its own year. The same World Bank indicator for every country.
Latest figure: 2025 Data last updated 2026-10-18 · current
Source: The World Bank Group CC BY 4.0
Monthly figures are computed by CalculatorLib from these data.
Source details and methodology
- The World Bank Group — World Development Indicators (NY.GNP.PCAP.CD, NY.GDP.PCAP.PP.CD, SL.UEM.TOTL.ZS)
FAQ
Is the EPF relief really capped? Yes — EPF plus life insurance relief is capped at RM4,000 for YA2024.
Who gets the RM400 rebate? Residents whose chargeable income is RM35,000 or less; a spouse with no income adds another RM400.
Is this an official figure? No. It is an estimate to plan with — always confirm with LHDN or a tax professional.