

What this calculator does
This tool estimates the annual personal income tax (NDFL, налог на доходы физических лиц) owed in Russia on one calendar year of gross income. It applies the progressive scale in force for income received from 2025 and reports the annual tax, effective rate, marginal rate, net income, average monthly figures and the tax in each band. It suits employees, freelancers, expatriates and anyone comparing take-home pay across income levels.
How to use it
Enter the gross annual income in rubles, before tax. Then choose the taxpayer status: tax resident, non-resident with qualifying work income, or non-resident with other income. Deductions are not entered, because none are modelled. The results update from these two inputs.
Formula
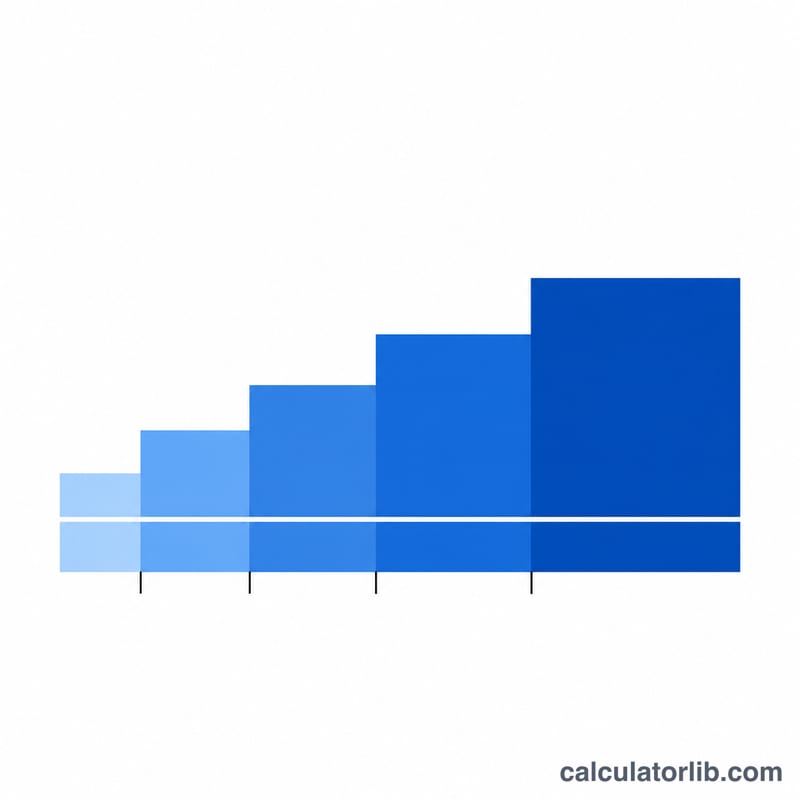
For residents and qualifying non-resident work income, each rate applies only to the slice of income inside its band:
$$T = 0.13\min(B,2.4M) + 0.15\max(0,\min(B,5M)-2.4M) + 0.18\max(0,\min(B,20M)-5M) + 0.20\max(0,\min(B,50M)-20M) + 0.22\max(0,B-50M)$$Here \(T\) = annual tax in RUB, \(B\) = gross annual income in RUB, and \(M\) = 1,000,000. For other non-resident income:
$$T = 0.30\,B$$The effective rate is \(t_{eff} = T/B \times 100\) (0 when \(B = 0\)), and net income is \(N = B - T\). Monthly figures are the annual values divided by 12.
Conventions and assumptions
- Bands for income received from 2025: up to 2,400,000 at 13%; above 2.4M to 5M at 15%; above 5M to 20M at 18%; above 20M to 50M at 20%; above 50M at 22%. Upper edges are inclusive, so exactly 2,400,000 stays in the 13% band.
- Progressive application: a rate hits only the part of income inside its band. Cumulative tax at the edges is 312,000 at 2.4M, 702,000 at 5M, 3,402,000 at 20M and 9,402,000 at 50M. This follows from the official term progressive scale; the fixed amounts in Art. 224 of the Tax Code were not checked.
- Status: residents and non-residents with listed work income (patent work, highly-qualified specialists, resettlement programme, Russian-flag ship crews, refugees, remote work for a Russian employer, payment for work, services or IP, EAEU citizens) use the same scale. Other non-resident income is taxed at 30%.
- Residency: a tax resident is present in Russia at least 183 calendar days within 12 consecutive months. The calculator does not count days.
- The tax base equals gross income; no standard, social or property deductions are subtracted.
- Not modelled: special rates for SVO pay and Far North allowances, 5% and 9% incomes, non-resident dividends, undisclosed securities income, 35% prizes and interest, patent advances, and separate Art. 210 p.6 bases.
- Results are not rounded to whole rubles; display uses 2 decimals. The tax period is one calendar year.
Worked example
A tax resident earns 1,200,000 RUB in a year. All of it falls in the 13% band:
$$T = 0.13 \times 1{,}200{,}000 = 156{,}000\,\text{RUB}$$$$N = 1{,}200{,}000 - 156{,}000 = 1{,}044{,}000\,\text{RUB}$$The effective rate is 13% and the marginal rate is 13%. Average monthly tax is \(156{,}000/12 = 13{,}000\) RUB and average monthly net income is \(1{,}044{,}000/12 = 87{,}000\) RUB. Tax in the 15%, 18%, 20%, 22% bands and the flat 30% line is 0.
Reading the result
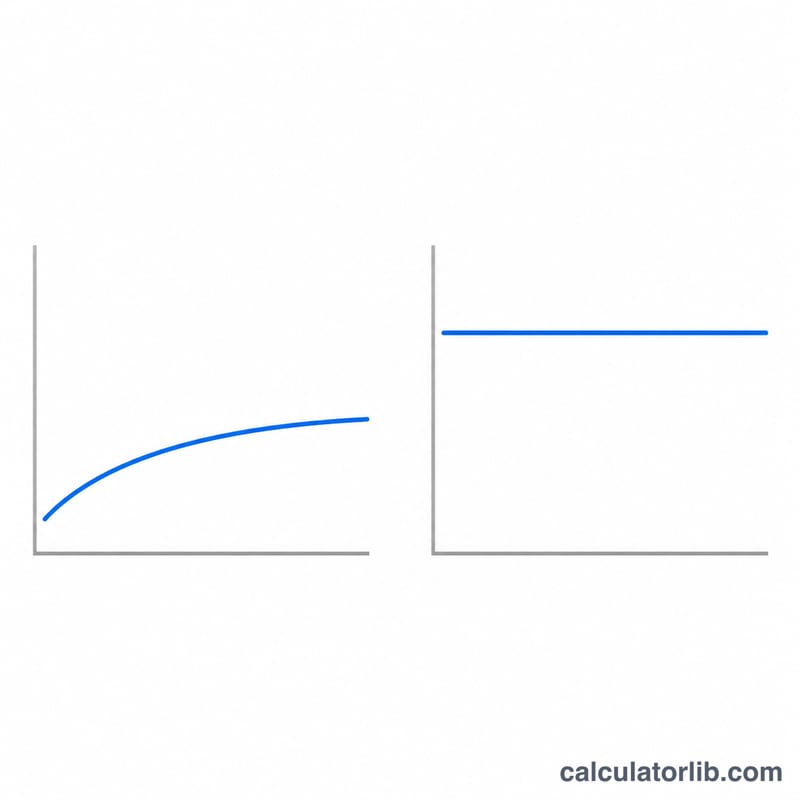
The marginal rate is the rate on the next ruble earned; the effective rate is the average share of income paid. The effective rate rises with income but never reaches 22%. Real withholding is done by the employer cumulatively by month, so income from several employers may be under-withheld during the year and settled later. This tool shows the annual liability only, without deductions or special regimes, and is an estimate rather than tax advice.
FAQ
Does the higher rate apply to all my income?
No. Each rate applies only to the slice of income inside its band.
Who pays 30%?
Non-residents with income other than the listed types of work income.
How is residency decided?
By presence in Russia for at least 183 days within 12 consecutive months.
Are deductions included?
No. The tax base equals the gross income entered.
Why is the tax not rounded to rubles?
The supplied source does not state the rounding rule, so raw values are shown to 2 decimals.
Sources
- Налог на доходы физических лиц (НДФЛ) — Федеральная налоговая служба России (ФНС России), income received from 2025.
















