What is the ACB Term Deposit Maturity Calculator?
This calculator estimates how much a term deposit (also called a fixed deposit or time deposit) will be worth when it matures. It uses the simple-interest method, where interest is calculated only on the original principal over the agreed term. Enter your deposit amount, the quoted annual interest rate, and the term length in months to see both the total maturity value and the interest you will earn.
How to use it
Type the principal you intend to deposit, the bank's advertised annual percentage rate, and how many months your money will be locked away. The calculator instantly returns the maturity amount you will receive at the end of the term, along with the breakdown of principal versus interest earned.
The formula explained
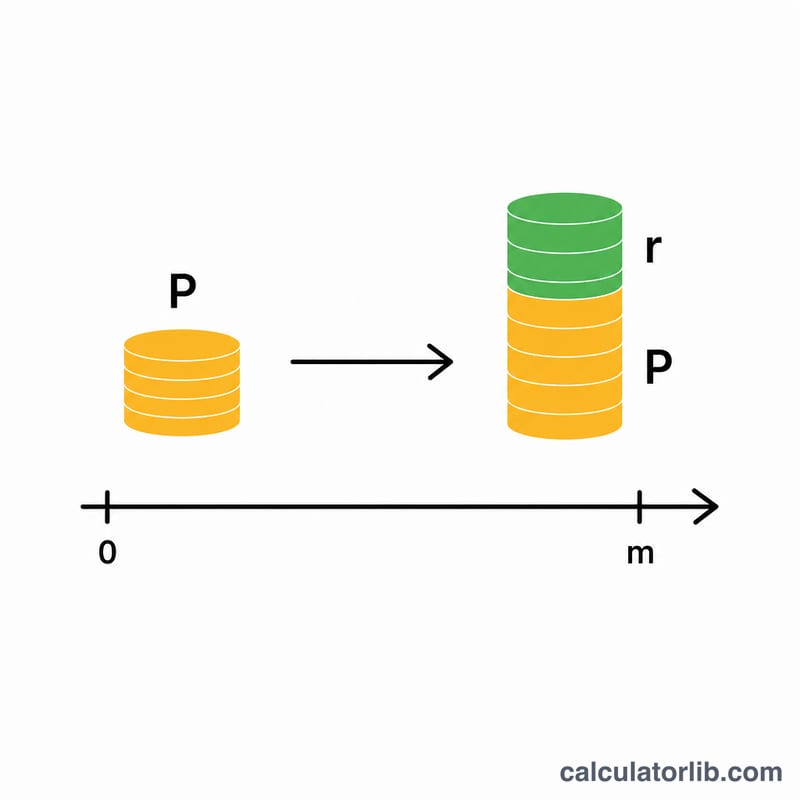
The maturity value is given by $$\text{Maturity} = \text{Principal} \times \left(1 + \frac{\text{AnnualRate}}{100} \times \frac{\text{Months}}{12}\right)$$. The rate is divided by 100 to convert a percentage into a decimal, and the term in months is divided by 12 to express it in years. Multiplying these gives the fraction of a full year's interest, which is added to the principal.
Worked example
Suppose you deposit 10,000 at an annual rate of 5% for a 12-month term. $$\text{Interest} = 10{,}000 \times 0.05 \times \frac{12}{12} = 500$$ The maturity value is \(10{,}000 + 500 = 10{,}500\). If the same deposit ran for only 6 months, the interest would be $$10{,}000 \times 0.05 \times 0.5 = 250$$ giving a maturity value of \(10{,}250\).
Maturity Across Different Terms and Rates
The table below shows the simple interest earned and the total maturity value for a range of realistic ACB term deposit scenarios. All figures use the simple-interest formula \(\text{Maturity} = P\left(1 + \frac{r}{100}\cdot\frac{m}{12}\right)\), where \(P\) is principal, \(r\) is the annual rate in percent, and \(m\) is the term in months. Interest earned is simply \(\text{Maturity} - P\).
| Principal | Annual Rate | Term (months) | Interest Earned | Maturity Value |
|---|---|---|---|---|
| 10,000 | 4% | 3 | 100.00 | 10,100.00 |
| 10,000 | 5% | 6 | 250.00 | 10,250.00 |
| 10,000 | 6% | 12 | 600.00 | 10,600.00 |
| 10,000 | 6% | 24 | 1,200.00 | 11,200.00 |
| 50,000 | 4% | 6 | 1,000.00 | 51,000.00 |
| 50,000 | 5% | 12 | 2,500.00 | 52,500.00 |
| 50,000 | 6% | 12 | 3,000.00 | 53,000.00 |
| 50,000 | 6% | 24 | 6,000.00 | 56,000.00 |
Notice that with simple interest, doubling the term exactly doubles the interest earned (compare the 12- and 24-month rows), because no interest is paid on previously accrued interest.
Key Terms Explained
- Principal
- The original amount of money you place into the term deposit. It is the base on which interest is calculated and is returned to you in full at maturity.
- Annual interest rate
- The stated yearly rate of return expressed as a percentage. For a deposit shorter or longer than one year, the rate is scaled by the fraction of a year the deposit is held.
- Term (tenor)
- The length of time the deposit is locked in, here measured in months. Funds are generally not available for withdrawal without penalty before the term ends.
- Maturity value
- The total amount payable at the end of the term — principal plus all interest earned.
- Simple interest
- Interest calculated only on the original principal, not on accumulated interest. It grows linearly with time rather than exponentially.
- Fixed (term) deposit
- A deposit committed for a set period at an agreed rate. In exchange for locking the funds away, the rate is typically higher and fixed for the term.
- Withholding tax
- Tax that a bank may deduct from interest income at source before paying it to the depositor. The actual interest you receive can therefore be lower than the gross figure this calculator shows.
Understanding Your Maturity Result
The maturity value shown by this calculator is the gross amount: principal plus simple interest, before any tax or fees are applied. If your jurisdiction or the bank applies a withholding tax on interest income, the cash you actually receive will be reduced by that amount. Always check the deposit terms for any account fees as well.
This tool uses simple interest, meaning interest accrues only on the original principal. A deposit that instead pays compound interest reinvests earned interest, so over the same period it yields more — and the gap widens with longer terms and more frequent compounding. If your deposit credits and reinvests interest periodically, a tool such as the ACB Compound Interest Deposit Calculator or a general compound interest calculator will model it more accurately.
Finally, the figure here is a nominal return. Your real (purchasing-power) return depends on inflation over the term: if prices rise faster than your interest rate, the real value of your money can fall even though the nominal balance grows. A real return on deposit after inflation calculator can help you gauge that effect.
This is general information for understanding how the calculation works, not financial or tax advice. Confirm current rates, tax treatment, and terms with ACB before making a decision.
Central bank policy rates today
The latest official policy rates of major central banks, updated automatically — the benchmark that bank deposit and loan rates follow.
- Federal Reserve · United States
- 3.75–4.00%
- As of
- 2026-11-13
- Change in 1 year
- 0 pp
Latest change Up +25 bp Federal Reserve changed its rate on 2026-09-17: from 3.50–3.75% to 3.75–4.00%.
| Central bank | Policy rate | As of | Change in 1 year |
|---|---|---|---|
| Banco Central do Brasil (Selic) · Brazil | 13.75% | 2026-11-16 | −1.25 pp |
| Banco de México · Mexico | 6.25% | 2026-11-10 | −1.00 pp |
| Federal Reserve · United States | 3.75–4.00% | 2026-11-13 | 0 pp |
| ECB | 2.50% | 2026-11-16 | +0.50 pp |
| Sveriges Riksbank · Sweden | 2.00% | 2026-11-16 | +0.25 pp |
| Saudi Central Bank (SAMA) · Saudi Arabia | 4.50% | 2026-10-29 | 0 pp |
| Reserve Bank of Australia · Australia | 4.60% | 2026-10-31 | +1.00 pp |
| Central Bank of the Republic of Türkiye · Türkiye | 36.00% | 2026-11-06 | −3.50 pp |
| Bank of Russia · Russia | 14.00% | 2026-11-10 | −2.50 pp |
| People’s Bank of China · China | 3.00% | 2026-11-10 | 0 pp |
| Bank of Canada · Canada | 2.50% | 2026-11-13 | +0.25 pp |
| Reserve Bank of India · India | 5.50% | 2026-10-19 | 0 pp |
| Bank of England · United Kingdom | 4.00% | 2026-11-16 | 0 pp |
| Bank of Japan · Japan | 1.25% | 2026-11-10 | +0.75 pp |
| Bank of Korea · South Korea | 3.00% | 2026-11-02 | +0.50 pp |
Federal Reserve: key rates and overnight market rates
The rates that frame monetary policy and the overnight market rate they steer, each with the date of its latest published value.
| Rate | Level | As of | Change in 1 year |
|---|---|---|---|
| Federal funds target range | 3.75–4.00% | 2026-11-13 | 0 pp |
| Effective federal funds rate (EFFR) | 3.88% | 2026-11-13 | 0 pp |
| Secured Overnight Financing Rate (SOFR) | 3.90% | 2026-11-13 | −0.10 pp |
Each rate keeps the date of its own latest published value; overnight market rates are published on the next business day.
Bank interest rates in Vietnam
What commercial banks in Vietnam charge borrowers and pay savers on average, as reported by the central bank to the World Bank (annual figures).
- Lending rate 2023
- 9.32%
- Deposit rate 2023
- 4.78%
- Real interest rate 2023
- 7.01%
- Lending minus deposit 2023
- 4.54 pp
| Year | Lending rate | Deposit rate |
|---|---|---|
| 2023 | 9.32% | 4.78% |
| 2022 | 8.01% | 3.82% |
| 2021 | 7.81% | 3.38% |
| 2020 | 7.65% | 4.12% |
| 2019 | 7.71% | 4.98% |
| 2018 | 7.37% | 4.74% |
The real interest rate is the lending rate adjusted for inflation (GDP deflator). The rate a particular bank offers you can differ.
Latest figure: 2026-11-13 Data last updated 2026-11-16 · current
Source: Banco Central do Brasil ODbL; Bank for International Settlements (BIS) Terms of permitted use of BIS statistics; Federal Reserve Bank of New York New York Fed Terms of Use; Board of Governors of the Federal Reserve System Public domain (U.S. government work); European Central Bank ECB reuse policy; The World Bank Group CC BY 4.0; Sveriges Riksbank Riksbank open data terms; Reserve Bank of Australia 2026 RBA copyright terms (Cash Rate); Bank of Canada Bank of Canada terms of use; Bank of England Open Government Licence v3.0
The one-year change is computed by CalculatorLib from these data. The EFFR and SOFR are subject to the Terms of Use posted at newyorkfed.org. The New York Fed is not responsible for publication of the EFFR and SOFR by CalculatorLib, does not sanction or endorse any particular republication, and has no liability for your use.
Source details and methodology
- Banco Central do Brasil
- Bank for International Settlements (BIS) — Central bank policy rates
- Federal Reserve Bank of New York — Reference rates (EFFR, SOFR)
- Board of Governors of the Federal Reserve System
- European Central Bank
- The World Bank Group — World Development Indicators (FR.INR.DPST, FR.INR.LEND, FR.INR.RINR, FR.INR.LNDP)
- Sveriges Riksbank
- Reserve Bank of Australia 2026
- Bank of Canada
- Bank of England
FAQ
Does this use simple or compound interest? It uses simple interest, which is the most common method for short fixed-term deposits where interest is paid at maturity.
Can I enter a term that is not a whole number of years? Yes. The term is measured in months, so any duration from 1 month upward is supported.
Is tax deducted from the result? No. The figure shown is the gross maturity value before any withholding tax or fees your bank may apply.