Early Mortgage Payoff Calculator

Early Mortgage Payoff Calculator

Growing AI Skill PRO

Enter Calculation

years
%
years months

Formula

Bk=Bk−1(1+r)−(M+Ek),Payoff=min⁡{k:Bk≤0}where{r=Rate (%)1200M=Loan amount·r(1+r)n(1+r)n−1,n=12Term (yr)N=12Remaining (yr)+Remaining (mo)B0=M·1−(1+r)−NrEk=Extra per month+[k≡0mod12]Extra per year+[k=1]One time\begin{gathered} B_{k} = B_{k-1}(1+r) - \left(M + E_{k}\right), \qquad \text{Payoff} = \min\{\,k : B_{k} \le 0\,\} \\[1.5em] \text{where}\quad \left\{ \begin{aligned} r &= \dfrac{\text{Rate (\%)}}{1200} \\ M &= \text{Loan amount} \cdot \dfrac{r\,(1+r)^{n}}{(1+r)^{n}-1},\quad n = 12\,\text{Term (yr)} \\ N &= 12\,\text{Remaining (yr)} + \text{Remaining (mo)} \\ B_{0} &= M \cdot \dfrac{1-(1+r)^{-N}}{r} \\ E_{k} &= \text{Extra per month} + \left[k \equiv 0 \bmod 12\right]\text{Extra per year} + \left[k = 1\right]\text{One time} \end{aligned} \right. \end{gathered}
Show calculation steps (1)
  1. Payoff With Biweekly Payments

    Bk=Bk−1(1+r)−(M+M2[k≡0mod6]),Payoff=min⁡{k:Bk≤0}where{r=Rate (%)1200M=Loan amount·r(1+r)n(1+r)n−1,n=12Term (yr)N=12Remaining (yr)+Remaining (mo)B0=M·1−(1+r)−Nr\begin{gathered} B_{k} = B_{k-1}(1+r) - \left(M + \tfrac{M}{2}\left[k \equiv 0 \bmod 6\right]\right), \qquad \text{Payoff} = \min\{\,k : B_{k} \le 0\,\} \\[1.5em] \text{where}\quad \left\{ \begin{aligned} r &= \dfrac{\text{Rate (\%)}}{1200} \\ M &= \text{Loan amount} \cdot \dfrac{r\,(1+r)^{n}}{(1+r)^{n}-1},\quad n = 12\,\text{Term (yr)} \\ N &= 12\,\text{Remaining (yr)} + \text{Remaining (mo)} \\ B_{0} &= M \cdot \dfrac{1-(1+r)^{-N}}{r} \end{aligned} \right. \end{gathered}

    Biweekly adds half a monthly payment on every 6th payoff month (twice a year): r = rate/1200; M = annuity payment on the original loan and term; N = remaining months; B0 = present value of the remaining payments.

Usage stats

Advertisement

Results

Payoff in
17 years 3 months
Remaining balance $372,217.43
Extra payment $500.00
Interest savings $122,306
Time savings 7 years 9 months
Interest reduction 26%
Time reduction 31%
Original With payoff
Monthly pay $2,398.20 $2,898.20
Total payments $863,352.76 $741,046.55
Total interest $463,352.76 $341,046.55
Remaining payments $719,460.63 $597,154.42
Remaining interest $347,243.20 $224,937.00
Payoff in months 300 207
Loan amount $400,000.00
Loan term 30 years
Months elapsed 60
Scheduled payment $2,398.20
Amortization schedule
Month Original With payoff
Interest Principal Balance Interest Principal Balance
1 $2,000.00 $398.20 $399,601.80 $2,000.00 $398.20 $399,601.80
2 $1,998.01 $400.19 $399,201.60 $1,998.01 $400.19 $399,201.60
3 $1,996.01 $402.19 $398,799.41 $1,996.01 $402.19 $398,799.41
4 $1,994.00 $404.20 $398,395.21 $1,994.00 $404.20 $398,395.21
5 $1,991.98 $406.22 $397,988.98 $1,991.98 $406.22 $397,988.98
6 $1,989.94 $408.26 $397,580.72 $1,989.94 $408.26 $397,580.72
7 $1,987.90 $410.30 $397,170.42 $1,987.90 $410.30 $397,170.42
8 $1,985.85 $412.35 $396,758.07 $1,985.85 $412.35 $396,758.07
9 $1,983.79 $414.41 $396,343.66 $1,983.79 $414.41 $396,343.66
10 $1,981.72 $416.48 $395,927.18 $1,981.72 $416.48 $395,927.18
11 $1,979.64 $418.56 $395,508.61 $1,979.64 $418.56 $395,508.61
12 $1,977.54 $420.66 $395,087.95 $1,977.54 $420.66 $395,087.95
Year 1
13 $1,975.44 $422.76 $394,665.19 $1,975.44 $422.76 $394,665.19
14 $1,973.33 $424.87 $394,240.31 $1,973.33 $424.87 $394,240.31
15 $1,971.20 $427.00 $393,813.31 $1,971.20 $427.00 $393,813.31
16 $1,969.07 $429.13 $393,384.18 $1,969.07 $429.13 $393,384.18
17 $1,966.92 $431.28 $392,952.90 $1,966.92 $431.28 $392,952.90
18 $1,964.76 $433.44 $392,519.46 $1,964.76 $433.44 $392,519.46
19 $1,962.60 $435.60 $392,083.85 $1,962.60 $435.60 $392,083.85
20 $1,960.42 $437.78 $391,646.07 $1,960.42 $437.78 $391,646.07
21 $1,958.23 $439.97 $391,206.10 $1,958.23 $439.97 $391,206.10
22 $1,956.03 $442.17 $390,763.93 $1,956.03 $442.17 $390,763.93
23 $1,953.82 $444.38 $390,319.55 $1,953.82 $444.38 $390,319.55
24 $1,951.60 $446.60 $389,872.94 $1,951.60 $446.60 $389,872.94
Year 2
25 $1,949.36 $448.84 $389,424.10 $1,949.36 $448.84 $389,424.10
26 $1,947.12 $451.08 $388,973.02 $1,947.12 $451.08 $388,973.02
27 $1,944.87 $453.33 $388,519.69 $1,944.87 $453.33 $388,519.69
28 $1,942.60 $455.60 $388,064.08 $1,942.60 $455.60 $388,064.08
29 $1,940.32 $457.88 $387,606.20 $1,940.32 $457.88 $387,606.20
30 $1,938.03 $460.17 $387,146.03 $1,938.03 $460.17 $387,146.03
31 $1,935.73 $462.47 $386,683.56 $1,935.73 $462.47 $386,683.56
32 $1,933.42 $464.78 $386,218.77 $1,933.42 $464.78 $386,218.77
33 $1,931.09 $467.11 $385,751.67 $1,931.09 $467.11 $385,751.67
34 $1,928.76 $469.44 $385,282.22 $1,928.76 $469.44 $385,282.22
35 $1,926.41 $471.79 $384,810.43 $1,926.41 $471.79 $384,810.43
36 $1,924.05 $474.15 $384,336.28 $1,924.05 $474.15 $384,336.28
Year 3
37 $1,921.68 $476.52 $383,859.76 $1,921.68 $476.52 $383,859.76
38 $1,919.30 $478.90 $383,380.86 $1,919.30 $478.90 $383,380.86
39 $1,916.90 $481.30 $382,899.56 $1,916.90 $481.30 $382,899.56
40 $1,914.50 $483.70 $382,415.85 $1,914.50 $483.70 $382,415.85
41 $1,912.08 $486.12 $381,929.73 $1,912.08 $486.12 $381,929.73
42 $1,909.65 $488.55 $381,441.18 $1,909.65 $488.55 $381,441.18
43 $1,907.21 $490.99 $380,950.18 $1,907.21 $490.99 $380,950.18
44 $1,904.75 $493.45 $380,456.73 $1,904.75 $493.45 $380,456.73
45 $1,902.28 $495.92 $379,960.81 $1,902.28 $495.92 $379,960.81
46 $1,899.80 $498.40 $379,462.41 $1,899.80 $498.40 $379,462.41
47 $1,897.31 $500.89 $378,961.52 $1,897.31 $500.89 $378,961.52
48 $1,894.81 $503.39 $378,458.13 $1,894.81 $503.39 $378,458.13
Year 4
49 $1,892.29 $505.91 $377,952.22 $1,892.29 $505.91 $377,952.22
50 $1,889.76 $508.44 $377,443.78 $1,889.76 $508.44 $377,443.78
51 $1,887.22 $510.98 $376,932.79 $1,887.22 $510.98 $376,932.79
52 $1,884.66 $513.54 $376,419.26 $1,884.66 $513.54 $376,419.26
53 $1,882.10 $516.10 $375,903.15 $1,882.10 $516.10 $375,903.15
54 $1,879.52 $518.68 $375,384.46 $1,879.52 $518.68 $375,384.46
55 $1,876.92 $521.28 $374,863.18 $1,876.92 $521.28 $374,863.18
56 $1,874.32 $523.88 $374,339.30 $1,874.32 $523.88 $374,339.30
57 $1,871.70 $526.50 $373,812.79 $1,871.70 $526.50 $373,812.79
58 $1,869.06 $529.14 $373,283.65 $1,869.06 $529.14 $373,283.65
59 $1,866.42 $531.78 $372,751.87 $1,866.42 $531.78 $372,751.87
60 $1,863.76 $534.44 $372,217.43 $1,863.76 $534.44 $372,217.43
Year 5
Payoff starts
61 $1,861.09 $537.11 $371,680.31 $1,861.09 $1,037.11 $371,180.31
62 $1,858.40 $539.80 $371,140.51 $1,855.90 $1,042.30 $370,138.01
63 $1,855.70 $542.50 $370,598.01 $1,850.69 $1,047.51 $369,090.50
64 $1,852.99 $545.21 $370,052.80 $1,845.45 $1,052.75 $368,037.75
65 $1,850.26 $547.94 $369,504.86 $1,840.19 $1,058.01 $366,979.74
66 $1,847.52 $550.68 $368,954.18 $1,834.90 $1,063.30 $365,916.43
67 $1,844.77 $553.43 $368,400.75 $1,829.58 $1,068.62 $364,847.81
68 $1,842.00 $556.20 $367,844.55 $1,824.24 $1,073.96 $363,773.85
69 $1,839.22 $558.98 $367,285.58 $1,818.87 $1,079.33 $362,694.52
70 $1,836.43 $561.77 $366,723.80 $1,813.47 $1,084.73 $361,609.79
71 $1,833.62 $564.58 $366,159.22 $1,808.05 $1,090.15 $360,519.63
72 $1,830.80 $567.40 $365,591.81 $1,802.60 $1,095.60 $359,424.03
Year 6
73 $1,827.96 $570.24 $365,021.57 $1,797.12 $1,101.08 $358,322.95
74 $1,825.11 $573.09 $364,448.47 $1,791.61 $1,106.59 $357,216.36
75 $1,822.24 $575.96 $363,872.52 $1,786.08 $1,112.12 $356,104.24
76 $1,819.36 $578.84 $363,293.68 $1,780.52 $1,117.68 $354,986.56
77 $1,816.47 $581.73 $362,711.94 $1,774.93 $1,123.27 $353,863.29
78 $1,813.56 $584.64 $362,127.30 $1,769.32 $1,128.88 $352,734.41
79 $1,810.64 $587.56 $361,539.73 $1,763.67 $1,134.53 $351,599.88
80 $1,807.70 $590.50 $360,949.23 $1,758.00 $1,140.20 $350,459.67
81 $1,804.75 $593.45 $360,355.77 $1,752.30 $1,145.90 $349,313.77
82 $1,801.78 $596.42 $359,759.35 $1,746.57 $1,151.63 $348,162.14
83 $1,798.80 $599.40 $359,159.95 $1,740.81 $1,157.39 $347,004.74
84 $1,795.80 $602.40 $358,557.54 $1,735.02 $1,163.18 $345,841.57
Year 7
85 $1,792.79 $605.41 $357,952.13 $1,729.21 $1,168.99 $344,672.57
86 $1,789.76 $608.44 $357,343.69 $1,723.36 $1,174.84 $343,497.73
87 $1,786.72 $611.48 $356,732.20 $1,717.49 $1,180.71 $342,317.02
88 $1,783.66 $614.54 $356,117.66 $1,711.59 $1,186.61 $341,130.40
89 $1,780.59 $617.61 $355,500.05 $1,705.65 $1,192.55 $339,937.85
90 $1,777.50 $620.70 $354,879.35 $1,699.69 $1,198.51 $338,739.34
91 $1,774.40 $623.80 $354,255.54 $1,693.70 $1,204.50 $337,534.83
92 $1,771.28 $626.92 $353,628.62 $1,687.67 $1,210.53 $336,324.31
93 $1,768.14 $630.06 $352,998.56 $1,681.62 $1,216.58 $335,107.73
94 $1,764.99 $633.21 $352,365.35 $1,675.54 $1,222.66 $333,885.06
95 $1,761.83 $636.37 $351,728.97 $1,669.43 $1,228.77 $332,656.28
96 $1,758.64 $639.56 $351,089.42 $1,663.28 $1,234.92 $331,421.36
Year 8
97 $1,755.45 $642.75 $350,446.66 $1,657.11 $1,241.09 $330,180.27
98 $1,752.23 $645.97 $349,800.69 $1,650.90 $1,247.30 $328,932.97
99 $1,749.00 $649.20 $349,151.49 $1,644.66 $1,253.54 $327,679.43
100 $1,745.76 $652.44 $348,499.05 $1,638.40 $1,259.80 $326,419.63
101 $1,742.50 $655.70 $347,843.34 $1,632.10 $1,266.10 $325,153.52
102 $1,739.22 $658.98 $347,184.36 $1,625.77 $1,272.43 $323,881.09
103 $1,735.92 $662.28 $346,522.08 $1,619.41 $1,278.79 $322,602.29
104 $1,732.61 $665.59 $345,856.49 $1,613.01 $1,285.19 $321,317.10
105 $1,729.28 $668.92 $345,187.57 $1,606.59 $1,291.61 $320,025.48
106 $1,725.94 $672.26 $344,515.30 $1,600.13 $1,298.07 $318,727.41
107 $1,722.58 $675.62 $343,839.68 $1,593.64 $1,304.56 $317,422.84
108 $1,719.20 $679.00 $343,160.67 $1,587.11 $1,311.09 $316,111.76
Year 9
109 $1,715.80 $682.40 $342,478.27 $1,580.56 $1,317.64 $314,794.11
110 $1,712.39 $685.81 $341,792.46 $1,573.97 $1,324.23 $313,469.88
111 $1,708.96 $689.24 $341,103.22 $1,567.35 $1,330.85 $312,139.03
112 $1,705.52 $692.68 $340,410.54 $1,560.70 $1,337.50 $310,801.52
113 $1,702.05 $696.15 $339,714.39 $1,554.01 $1,344.19 $309,457.33
114 $1,698.57 $699.63 $339,014.76 $1,547.29 $1,350.91 $308,106.41
115 $1,695.07 $703.13 $338,311.63 $1,540.53 $1,357.67 $306,748.74
116 $1,691.56 $706.64 $337,604.98 $1,533.74 $1,364.46 $305,384.28
117 $1,688.02 $710.18 $336,894.81 $1,526.92 $1,371.28 $304,013.00
118 $1,684.47 $713.73 $336,181.08 $1,520.07 $1,378.13 $302,634.87
119 $1,680.91 $717.29 $335,463.78 $1,513.17 $1,385.03 $301,249.84
120 $1,677.32 $720.88 $334,742.90 $1,506.25 $1,391.95 $299,857.88
Year 10
121 $1,673.71 $724.49 $334,018.41 $1,499.29 $1,398.91 $298,458.97
122 $1,670.09 $728.11 $333,290.30 $1,492.29 $1,405.91 $297,053.06
123 $1,666.45 $731.75 $332,558.55 $1,485.27 $1,412.93 $295,640.13
124 $1,662.79 $735.41 $331,823.14 $1,478.20 $1,420.00 $294,220.13
125 $1,659.12 $739.08 $331,084.06 $1,471.10 $1,427.10 $292,793.02
126 $1,655.42 $742.78 $330,341.27 $1,463.97 $1,434.23 $291,358.79
127 $1,651.71 $746.49 $329,594.78 $1,456.79 $1,441.41 $289,917.38
128 $1,647.97 $750.23 $328,844.55 $1,449.59 $1,448.61 $288,468.76
129 $1,644.22 $753.98 $328,090.57 $1,442.34 $1,455.86 $287,012.91
130 $1,640.45 $757.75 $327,332.82 $1,435.06 $1,463.14 $285,549.77
131 $1,636.66 $761.54 $326,571.28 $1,427.75 $1,470.45 $284,079.32
132 $1,632.86 $765.34 $325,805.94 $1,420.40 $1,477.80 $282,601.51
Year 11
133 $1,629.03 $769.17 $325,036.77 $1,413.01 $1,485.19 $281,116.32
134 $1,625.18 $773.02 $324,263.75 $1,405.58 $1,492.62 $279,623.69
135 $1,621.32 $776.88 $323,486.86 $1,398.12 $1,500.08 $278,123.61
136 $1,617.43 $780.77 $322,706.10 $1,390.62 $1,507.58 $276,616.03
137 $1,613.53 $784.67 $321,921.42 $1,383.08 $1,515.12 $275,100.91
138 $1,609.61 $788.59 $321,132.83 $1,375.50 $1,522.70 $273,578.21
139 $1,605.66 $792.54 $320,340.29 $1,367.89 $1,530.31 $272,047.90
140 $1,601.70 $796.50 $319,543.79 $1,360.24 $1,537.96 $270,509.93
141 $1,597.72 $800.48 $318,743.31 $1,352.55 $1,545.65 $268,964.28
142 $1,593.72 $804.48 $317,938.82 $1,344.82 $1,553.38 $267,410.90
143 $1,589.69 $808.51 $317,130.31 $1,337.05 $1,561.15 $265,849.75
144 $1,585.65 $812.55 $316,317.76 $1,329.25 $1,568.95 $264,280.80
Year 12
145 $1,581.59 $816.61 $315,501.15 $1,321.40 $1,576.80 $262,704.00
146 $1,577.51 $820.69 $314,680.45 $1,313.52 $1,584.68 $261,119.32
147 $1,573.40 $824.80 $313,855.65 $1,305.60 $1,592.60 $259,526.71
148 $1,569.28 $828.92 $313,026.73 $1,297.63 $1,600.57 $257,926.15
149 $1,565.13 $833.07 $312,193.66 $1,289.63 $1,608.57 $256,317.57
150 $1,560.97 $837.23 $311,356.43 $1,281.59 $1,616.61 $254,700.96
151 $1,556.78 $841.42 $310,515.01 $1,273.50 $1,624.70 $253,076.26
152 $1,552.58 $845.62 $309,669.38 $1,265.38 $1,632.82 $251,443.44
153 $1,548.35 $849.85 $308,819.53 $1,257.22 $1,640.98 $249,802.46
154 $1,544.10 $854.10 $307,965.42 $1,249.01 $1,649.19 $248,153.27
155 $1,539.83 $858.37 $307,107.05 $1,240.77 $1,657.43 $246,495.83
156 $1,535.54 $862.66 $306,244.38 $1,232.48 $1,665.72 $244,830.11
Year 13
157 $1,531.22 $866.98 $305,377.40 $1,224.15 $1,674.05 $243,156.06
158 $1,526.89 $871.31 $304,506.08 $1,215.78 $1,682.42 $241,473.64
159 $1,522.53 $875.67 $303,630.41 $1,207.37 $1,690.83 $239,782.80
160 $1,518.15 $880.05 $302,750.36 $1,198.91 $1,699.29 $238,083.51
161 $1,513.75 $884.45 $301,865.91 $1,190.42 $1,707.78 $236,375.73
162 $1,509.33 $888.87 $300,977.04 $1,181.88 $1,716.32 $234,659.41
163 $1,504.89 $893.31 $300,083.72 $1,173.30 $1,724.90 $232,934.50
164 $1,500.42 $897.78 $299,185.94 $1,164.67 $1,733.53 $231,200.97
165 $1,495.93 $902.27 $298,283.67 $1,156.00 $1,742.20 $229,458.77
166 $1,491.42 $906.78 $297,376.88 $1,147.29 $1,750.91 $227,707.87
167 $1,486.88 $911.32 $296,465.57 $1,138.54 $1,759.66 $225,948.20
168 $1,482.33 $915.87 $295,549.69 $1,129.74 $1,768.46 $224,179.74
Year 14
169 $1,477.75 $920.45 $294,629.24 $1,120.90 $1,777.30 $222,402.44
170 $1,473.15 $925.05 $293,704.18 $1,112.01 $1,786.19 $220,616.25
171 $1,468.52 $929.68 $292,774.50 $1,103.08 $1,795.12 $218,821.13
172 $1,463.87 $934.33 $291,840.17 $1,094.11 $1,804.09 $217,017.03
173 $1,459.20 $939.00 $290,901.17 $1,085.09 $1,813.11 $215,203.91
174 $1,454.51 $943.69 $289,957.47 $1,076.02 $1,822.18 $213,381.73
175 $1,449.79 $948.41 $289,009.06 $1,066.91 $1,831.29 $211,550.44
176 $1,445.05 $953.15 $288,055.90 $1,057.75 $1,840.45 $209,709.99
177 $1,440.28 $957.92 $287,097.98 $1,048.55 $1,849.65 $207,860.34
178 $1,435.49 $962.71 $286,135.27 $1,039.30 $1,858.90 $206,001.44
179 $1,430.68 $967.52 $285,167.74 $1,030.01 $1,868.19 $204,133.24
180 $1,425.84 $972.36 $284,195.38 $1,020.67 $1,877.53 $202,255.70
Year 15
181 $1,420.98 $977.22 $283,218.15 $1,011.28 $1,886.92 $200,368.78
182 $1,416.09 $982.11 $282,236.04 $1,001.84 $1,896.36 $198,472.42
183 $1,411.18 $987.02 $281,249.02 $992.36 $1,905.84 $196,566.58
184 $1,406.25 $991.95 $280,257.06 $982.83 $1,915.37 $194,651.21
185 $1,401.29 $996.91 $279,260.15 $973.26 $1,924.94 $192,726.27
186 $1,396.30 $1,001.90 $278,258.24 $963.63 $1,934.57 $190,791.70
187 $1,391.29 $1,006.91 $277,251.33 $953.96 $1,944.24 $188,847.45
188 $1,386.26 $1,011.94 $276,239.39 $944.24 $1,953.96 $186,893.49
189 $1,381.20 $1,017.00 $275,222.38 $934.47 $1,963.73 $184,929.75
190 $1,376.11 $1,022.09 $274,200.29 $924.65 $1,973.55 $182,956.20
191 $1,371.00 $1,027.20 $273,173.09 $914.78 $1,983.42 $180,972.78
192 $1,365.87 $1,032.33 $272,140.76 $904.86 $1,993.34 $178,979.44
Year 16
193 $1,360.70 $1,037.50 $271,103.26 $894.90 $2,003.30 $176,976.14
194 $1,355.52 $1,042.68 $270,060.57 $884.88 $2,013.32 $174,962.81
195 $1,350.30 $1,047.90 $269,012.67 $874.81 $2,023.39 $172,939.43
196 $1,345.06 $1,053.14 $267,959.53 $864.70 $2,033.50 $170,905.92
197 $1,339.80 $1,058.40 $266,901.13 $854.53 $2,043.67 $168,862.25
198 $1,334.51 $1,063.69 $265,837.43 $844.31 $2,053.89 $166,808.36
199 $1,329.19 $1,069.01 $264,768.42 $834.04 $2,064.16 $164,744.20
200 $1,323.84 $1,074.36 $263,694.06 $823.72 $2,074.48 $162,669.72
201 $1,318.47 $1,079.73 $262,614.33 $813.35 $2,084.85 $160,584.86
202 $1,313.07 $1,085.13 $261,529.19 $802.92 $2,095.28 $158,489.59
203 $1,307.65 $1,090.55 $260,438.64 $792.45 $2,105.75 $156,383.83
204 $1,302.19 $1,096.01 $259,342.63 $781.92 $2,116.28 $154,267.55
Year 17
205 $1,296.71 $1,101.49 $258,241.14 $771.34 $2,126.86 $152,140.68
206 $1,291.21 $1,106.99 $257,134.14 $760.70 $2,137.50 $150,003.19
207 $1,285.67 $1,112.53 $256,021.61 $750.02 $2,148.18 $147,855.00
208 $1,280.11 $1,118.09 $254,903.52 $739.27 $2,158.93 $145,696.07
209 $1,274.52 $1,123.68 $253,779.83 $728.48 $2,169.72 $143,526.35
210 $1,268.90 $1,129.30 $252,650.53 $717.63 $2,180.57 $141,345.78
211 $1,263.25 $1,134.95 $251,515.58 $706.73 $2,191.47 $139,154.31
212 $1,257.58 $1,140.62 $250,374.96 $695.77 $2,202.43 $136,951.88
213 $1,251.87 $1,146.33 $249,228.63 $684.76 $2,213.44 $134,738.43
214 $1,246.14 $1,152.06 $248,076.57 $673.69 $2,224.51 $132,513.92
215 $1,240.38 $1,157.82 $246,918.75 $662.57 $2,235.63 $130,278.29
216 $1,234.59 $1,163.61 $245,755.14 $651.39 $2,246.81 $128,031.48
Year 18
217 $1,228.78 $1,169.42 $244,585.72 $640.16 $2,258.04 $125,773.44
218 $1,222.93 $1,175.27 $243,410.44 $628.87 $2,269.33 $123,504.10
219 $1,217.05 $1,181.15 $242,229.29 $617.52 $2,280.68 $121,223.42
220 $1,211.15 $1,187.05 $241,042.24 $606.12 $2,292.08 $118,931.33
221 $1,205.21 $1,192.99 $239,849.25 $594.66 $2,303.54 $116,627.79
222 $1,199.25 $1,198.95 $238,650.29 $583.14 $2,315.06 $114,312.73
223 $1,193.25 $1,204.95 $237,445.34 $571.56 $2,326.64 $111,986.09
224 $1,187.23 $1,210.97 $236,234.37 $559.93 $2,338.27 $109,647.82
225 $1,181.17 $1,217.03 $235,017.34 $548.24 $2,349.96 $107,297.85
226 $1,175.09 $1,223.11 $233,794.22 $536.49 $2,361.71 $104,936.14
227 $1,168.97 $1,229.23 $232,564.99 $524.68 $2,373.52 $102,562.62
228 $1,162.82 $1,235.38 $231,329.61 $512.81 $2,385.39 $100,177.23
Year 19
229 $1,156.65 $1,241.55 $230,088.06 $500.89 $2,397.31 $97,779.91
230 $1,150.44 $1,247.76 $228,840.30 $488.90 $2,409.30 $95,370.61
231 $1,144.20 $1,254.00 $227,586.30 $476.85 $2,421.35 $92,949.26
232 $1,137.93 $1,260.27 $226,326.03 $464.75 $2,433.45 $90,515.81
233 $1,131.63 $1,266.57 $225,059.45 $452.58 $2,445.62 $88,070.18
234 $1,125.30 $1,272.90 $223,786.55 $440.35 $2,457.85 $85,612.33
235 $1,118.93 $1,279.27 $222,507.28 $428.06 $2,470.14 $83,142.19
236 $1,112.54 $1,285.66 $221,221.61 $415.71 $2,482.49 $80,659.70
237 $1,106.11 $1,292.09 $219,929.52 $403.30 $2,494.90 $78,164.80
238 $1,099.65 $1,298.55 $218,630.96 $390.82 $2,507.38 $75,657.42
239 $1,093.15 $1,305.05 $217,325.92 $378.29 $2,519.91 $73,137.50
240 $1,086.63 $1,311.57 $216,014.34 $365.69 $2,532.51 $70,604.99
Year 20
241 $1,080.07 $1,318.13 $214,696.21 $353.02 $2,545.18 $68,059.81
242 $1,073.48 $1,324.72 $213,371.49 $340.30 $2,557.90 $65,501.91
243 $1,066.86 $1,331.34 $212,040.15 $327.51 $2,570.69 $62,931.22
244 $1,060.20 $1,338.00 $210,702.15 $314.66 $2,583.54 $60,347.67
245 $1,053.51 $1,344.69 $209,357.46 $301.74 $2,596.46 $57,751.21
246 $1,046.79 $1,351.41 $208,006.04 $288.76 $2,609.44 $55,141.76
247 $1,040.03 $1,358.17 $206,647.87 $275.71 $2,622.49 $52,519.27
248 $1,033.24 $1,364.96 $205,282.91 $262.60 $2,635.60 $49,883.66
249 $1,026.41 $1,371.79 $203,911.12 $249.42 $2,648.78 $47,234.88
250 $1,019.56 $1,378.64 $202,532.47 $236.17 $2,662.03 $44,572.85
251 $1,012.66 $1,385.54 $201,146.93 $222.86 $2,675.34 $41,897.51
252 $1,005.73 $1,392.47 $199,754.47 $209.49 $2,688.71 $39,208.80
Year 21
253 $998.77 $1,399.43 $198,355.04 $196.04 $2,702.16 $36,506.64
254 $991.78 $1,406.42 $196,948.61 $182.53 $2,715.67 $33,790.97
255 $984.74 $1,413.46 $195,535.15 $168.95 $2,729.25 $31,061.72
256 $977.68 $1,420.52 $194,114.62 $155.31 $2,742.89 $28,318.83
257 $970.57 $1,427.63 $192,686.99 $141.59 $2,756.61 $25,562.22
258 $963.43 $1,434.77 $191,252.23 $127.81 $2,770.39 $22,791.83
259 $956.26 $1,441.94 $189,810.29 $113.96 $2,784.24 $20,007.59
260 $949.05 $1,449.15 $188,361.14 $100.04 $2,798.16 $17,209.42
261 $941.81 $1,456.39 $186,904.74 $86.05 $2,812.15 $14,397.27
262 $934.52 $1,463.68 $185,441.06 $71.99 $2,826.21 $11,571.05
263 $927.21 $1,470.99 $183,970.06 $57.86 $2,840.34 $8,730.71
264 $919.85 $1,478.35 $182,491.71 $43.65 $2,854.55 $5,876.16
Year 22
265 $912.46 $1,485.74 $181,005.97 $29.38 $2,868.82 $3,007.34
266 $905.03 $1,493.17 $179,512.80 $15.04 $2,883.16 $124.17
267 $897.56 $1,500.64 $178,012.16 $0.62 $124.17 $0.00
268 $890.06 $1,508.14 $176,504.02 $0.00 $0.00 $0.00
269 $882.52 $1,515.68 $174,988.34 $0.00 $0.00 $0.00
270 $874.94 $1,523.26 $173,465.07 $0.00 $0.00 $0.00
271 $867.33 $1,530.87 $171,934.20 $0.00 $0.00 $0.00
272 $859.67 $1,538.53 $170,395.67 $0.00 $0.00 $0.00
273 $851.98 $1,546.22 $168,849.44 $0.00 $0.00 $0.00
274 $844.25 $1,553.95 $167,295.49 $0.00 $0.00 $0.00
275 $836.48 $1,561.72 $165,733.76 $0.00 $0.00 $0.00
276 $828.67 $1,569.53 $164,164.23 $0.00 $0.00 $0.00
Year 23
277 $820.82 $1,577.38 $162,586.85 $0.00 $0.00 $0.00
278 $812.93 $1,585.27 $161,001.58 $0.00 $0.00 $0.00
279 $805.01 $1,593.19 $159,408.39 $0.00 $0.00 $0.00
280 $797.04 $1,601.16 $157,807.23 $0.00 $0.00 $0.00
281 $789.04 $1,609.16 $156,198.06 $0.00 $0.00 $0.00
282 $780.99 $1,617.21 $154,580.85 $0.00 $0.00 $0.00
283 $772.90 $1,625.30 $152,955.55 $0.00 $0.00 $0.00
284 $764.78 $1,633.42 $151,322.13 $0.00 $0.00 $0.00
285 $756.61 $1,641.59 $149,680.54 $0.00 $0.00 $0.00
286 $748.40 $1,649.80 $148,030.74 $0.00 $0.00 $0.00
287 $740.15 $1,658.05 $146,372.69 $0.00 $0.00 $0.00
288 $731.86 $1,666.34 $144,706.35 $0.00 $0.00 $0.00
Year 24
289 $723.53 $1,674.67 $143,031.68 $0.00 $0.00 $0.00
290 $715.16 $1,683.04 $141,348.64 $0.00 $0.00 $0.00
291 $706.74 $1,691.46 $139,657.18 $0.00 $0.00 $0.00
292 $698.29 $1,699.91 $137,957.26 $0.00 $0.00 $0.00
293 $689.79 $1,708.41 $136,248.84 $0.00 $0.00 $0.00
294 $681.24 $1,716.96 $134,531.89 $0.00 $0.00 $0.00
295 $672.66 $1,725.54 $132,806.34 $0.00 $0.00 $0.00
296 $664.03 $1,734.17 $131,072.17 $0.00 $0.00 $0.00
297 $655.36 $1,742.84 $129,329.33 $0.00 $0.00 $0.00
298 $646.65 $1,751.55 $127,577.78 $0.00 $0.00 $0.00
299 $637.89 $1,760.31 $125,817.46 $0.00 $0.00 $0.00
300 $629.09 $1,769.11 $124,048.35 $0.00 $0.00 $0.00
Year 25
301 $620.24 $1,777.96 $122,270.39 $0.00 $0.00 $0.00
302 $611.35 $1,786.85 $120,483.54 $0.00 $0.00 $0.00
303 $602.42 $1,795.78 $118,687.75 $0.00 $0.00 $0.00
304 $593.44 $1,804.76 $116,882.99 $0.00 $0.00 $0.00
305 $584.41 $1,813.79 $115,069.20 $0.00 $0.00 $0.00
306 $575.35 $1,822.85 $113,246.35 $0.00 $0.00 $0.00
307 $566.23 $1,831.97 $111,414.38 $0.00 $0.00 $0.00
308 $557.07 $1,841.13 $109,573.25 $0.00 $0.00 $0.00
309 $547.87 $1,850.33 $107,722.91 $0.00 $0.00 $0.00
310 $538.61 $1,859.59 $105,863.32 $0.00 $0.00 $0.00
311 $529.32 $1,868.88 $103,994.44 $0.00 $0.00 $0.00
312 $519.97 $1,878.23 $102,116.21 $0.00 $0.00 $0.00
Year 26
313 $510.58 $1,887.62 $100,228.59 $0.00 $0.00 $0.00
314 $501.14 $1,897.06 $98,331.53 $0.00 $0.00 $0.00
315 $491.66 $1,906.54 $96,424.98 $0.00 $0.00 $0.00
316 $482.12 $1,916.08 $94,508.91 $0.00 $0.00 $0.00
317 $472.54 $1,925.66 $92,583.25 $0.00 $0.00 $0.00
318 $462.92 $1,935.28 $90,647.96 $0.00 $0.00 $0.00
319 $453.24 $1,944.96 $88,703.00 $0.00 $0.00 $0.00
320 $443.51 $1,954.69 $86,748.31 $0.00 $0.00 $0.00
321 $433.74 $1,964.46 $84,783.85 $0.00 $0.00 $0.00
322 $423.92 $1,974.28 $82,809.57 $0.00 $0.00 $0.00
323 $414.05 $1,984.15 $80,825.42 $0.00 $0.00 $0.00
324 $404.13 $1,994.07 $78,831.34 $0.00 $0.00 $0.00
Year 27
325 $394.16 $2,004.04 $76,827.29 $0.00 $0.00 $0.00
326 $384.14 $2,014.06 $74,813.23 $0.00 $0.00 $0.00
327 $374.07 $2,024.13 $72,789.09 $0.00 $0.00 $0.00
328 $363.95 $2,034.25 $70,754.84 $0.00 $0.00 $0.00
329 $353.77 $2,044.43 $68,710.41 $0.00 $0.00 $0.00
330 $343.55 $2,054.65 $66,655.76 $0.00 $0.00 $0.00
331 $333.28 $2,064.92 $64,590.84 $0.00 $0.00 $0.00
332 $322.95 $2,075.25 $62,515.59 $0.00 $0.00 $0.00
333 $312.58 $2,085.62 $60,429.96 $0.00 $0.00 $0.00
334 $302.15 $2,096.05 $58,333.91 $0.00 $0.00 $0.00
335 $291.67 $2,106.53 $56,227.38 $0.00 $0.00 $0.00
336 $281.14 $2,117.06 $54,110.31 $0.00 $0.00 $0.00
Year 28
337 $270.55 $2,127.65 $51,982.66 $0.00 $0.00 $0.00
338 $259.91 $2,138.29 $49,844.37 $0.00 $0.00 $0.00
339 $249.22 $2,148.98 $47,695.39 $0.00 $0.00 $0.00
340 $238.48 $2,159.72 $45,535.67 $0.00 $0.00 $0.00
341 $227.68 $2,170.52 $43,365.14 $0.00 $0.00 $0.00
342 $216.83 $2,181.37 $41,183.77 $0.00 $0.00 $0.00
343 $205.92 $2,192.28 $38,991.49 $0.00 $0.00 $0.00
344 $194.96 $2,203.24 $36,788.24 $0.00 $0.00 $0.00
345 $183.94 $2,214.26 $34,573.98 $0.00 $0.00 $0.00
346 $172.87 $2,225.33 $32,348.65 $0.00 $0.00 $0.00
347 $161.74 $2,236.46 $30,112.19 $0.00 $0.00 $0.00
348 $150.56 $2,247.64 $27,864.55 $0.00 $0.00 $0.00
Year 29
349 $139.32 $2,258.88 $25,605.67 $0.00 $0.00 $0.00
350 $128.03 $2,270.17 $23,335.49 $0.00 $0.00 $0.00
351 $116.68 $2,281.52 $21,053.97 $0.00 $0.00 $0.00
352 $105.27 $2,292.93 $18,761.04 $0.00 $0.00 $0.00
353 $93.81 $2,304.39 $16,456.64 $0.00 $0.00 $0.00
354 $82.28 $2,315.92 $14,140.72 $0.00 $0.00 $0.00
355 $70.70 $2,327.50 $11,813.22 $0.00 $0.00 $0.00
356 $59.07 $2,339.13 $9,474.09 $0.00 $0.00 $0.00
357 $47.37 $2,350.83 $7,123.26 $0.00 $0.00 $0.00
358 $35.62 $2,362.58 $4,760.67 $0.00 $0.00 $0.00
359 $23.80 $2,374.40 $2,386.27 $0.00 $0.00 $0.00
360 $11.93 $2,386.27 $0.00 $0.00 $0.00 $0.00
Year 30

Report an error on this page

What this calculator tells you

This tool takes a mortgage you are already part-way through and works out what happens if you attack it — extra every month, extra every year, a one-off lump sum, a "biweekly" acceleration, or paying the balance off today. It reports when the loan actually clears, the interest you avoid, and a month-by-month schedule set beside the one you are on now.

People reach for it at a specific moment: a raise, a bonus, an inheritance, or a refinance quote. It answers "is $500 a month worth it?" with a number of years and a number of dollars — the only honest way to compare that $500 against anything else you could do with it.
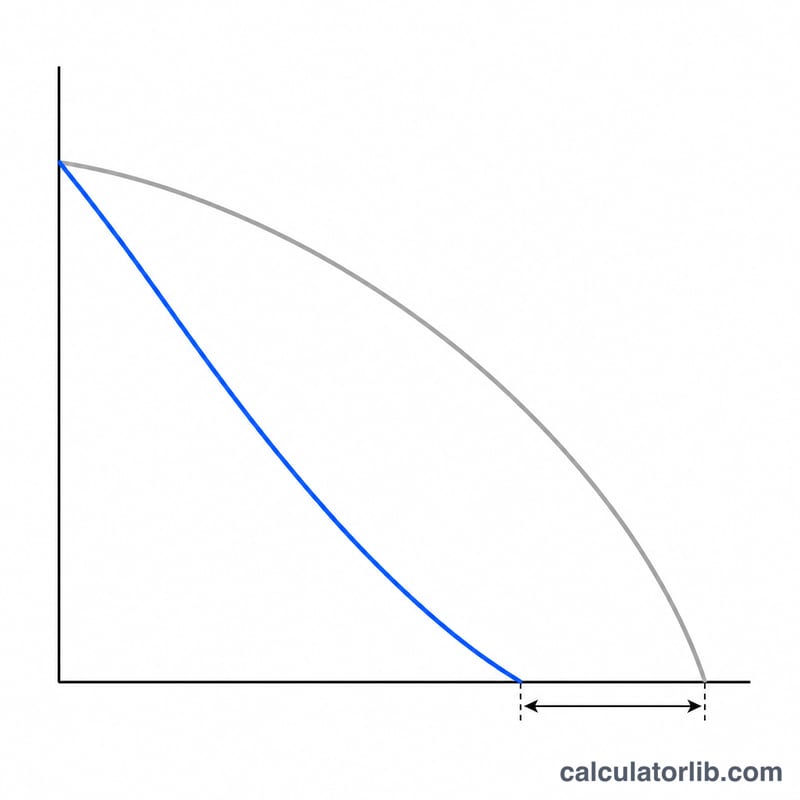
Two mortgage balance curves declining to zero, the extra-payment curve reaching zero earlier than the original
Extra payments push the balance to zero sooner; the arrow marks the months saved.

Filling in the boxes

Everything here comes off your original loan documents and your most recent statement.

Input Where it comes from Typical range
Original loan amount The closing documents — the amount borrowed on day one, not today's balance. $100,000 – $1,000,000
Original loan term Closing documents. Fractions are allowed, and are rounded up to a whole month. 15, 20 or 30 years
Interest rate Your note rate, annual, before fees. Must be above zero. 2.5% – 9%
Remaining term (years + months) Your statement, or count the payments left. The two boxes add together. Anything up to the full term
Repayment option Your choice of strategy: extra payments, biweekly, pay it all off now, or no change. —
Extra per month / per year / one time Whatever you can actually commit to. Used only under the extra-payments option. $50 – $2,000 monthly

Today's balance is derived, not entered: the original loan is amortized forward to where your remaining term begins. If the balance it reports differs from your statement, nudge the remaining term until the two agree.

The math

The scheduled payment is the standard annuity payment on the original loan, with \(L\) = original amount, \(n\) = term in months, and \(r\) = monthly rate (annual rate ÷ 12 ÷ 100):

$$p=\frac{L\times r}{1-(1+r)^{-n}}$$

With \(s\) = months already elapsed (original term minus remaining term), the balance the strategy starts from is that loan run forward \(s\) months:

$$B=L(1+r)^{s}-p\times\frac{(1+r)^{s}-1}{r}$$

From there the payoff runs month by month, where \(e_k\) is the extra added to payment \(k\) (counting \(k=0\) as your next payment), until the balance reaches zero:

$$B_{k+1}=B_k(1+r)-(p+e_k)$$

Interest saved is the difference between the two lifetime interest figures, and each lifetime figure is total payments minus the original loan amount:

$$\text{Interest saved}=\left(n\times p-L\right)-\left(s\times p+\textstyle\sum_k \text{pay}_k-L\right)$$
Advertisement
Diagram splitting a monthly payment into interest, principal and an extra amount, with principal and extra reducing the balance
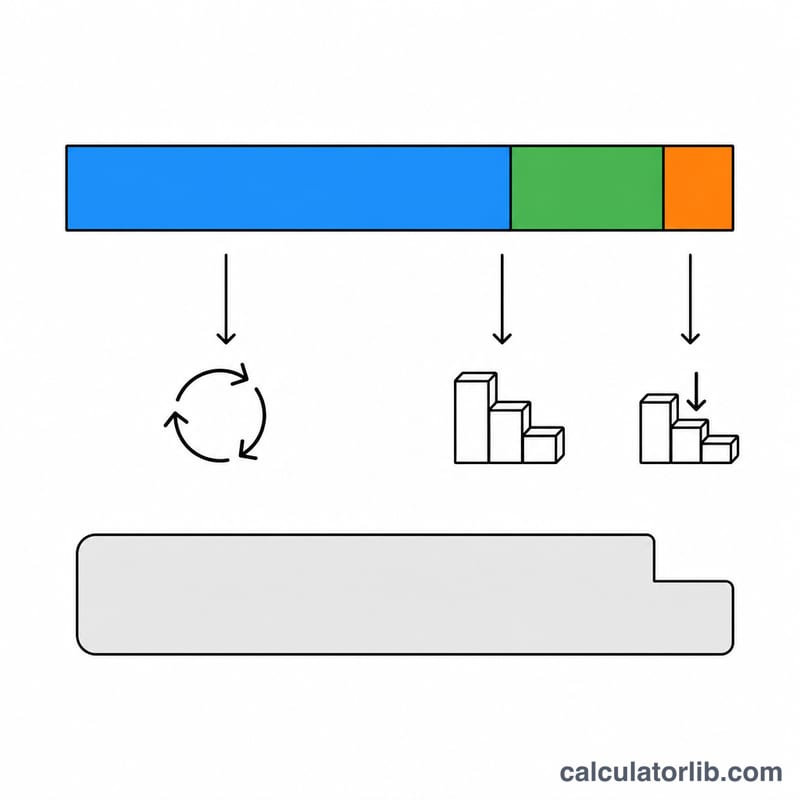
Each payment splits into interest and principal; any extra amount goes straight to the balance.

Worked example

A $400,000 loan, 30-year term, 6% fixed, with 25 years left, and you start adding $500 a month.

Monthly rate and term first: \(r=0.06/12=0.005\), \(n=360\), remaining \(=300\) months, so \(s=60\) months are already behind you.

$$p=\frac{400{,}000\times0.005}{1-(1.005)^{-360}}=2398.2021\ldots\rightarrow \$2{,}398.20$$

The balance standing after those 60 payments:

$$B=400{,}000(1.005)^{60}-2398.2021\times\frac{(1.005)^{60}-1}{0.005}=\$372{,}217.43$$

Now each month pays \(2398.2021+500=\$2{,}898.20\). Running that forward, the balance hits zero on payment 207 — 17 years and 3 months, against the 300 months (25 years) you had left. Time saved: \(300-207=93\) months, or 7 years and 9 months.

Those 207 payments total $597,154.42. Add back the 60 payments you already made at the old amount:

$$60\times2398.2021=\$143{,}892.13\qquad 143{,}892.13+597{,}154.42=\$741{,}046.55$$

Lifetime interest either way, and the gap between them:

$$463{,}352.76-341{,}046.55=\$122{,}306.21\rightarrow \$122{,}306\text{ saved}$$ $$\frac{122{,}306.21}{463{,}352.76}\times100=26.4\%\rightarrow \text{26\% less interest}$$

Rules that catch people out

"Total payments" includes money you already spent. The with-payoff total of $741,046.55 above contains the $143,892.13 you paid before the strategy began. If what you want is "what will this cost me from today," read the Remaining payments row instead — $597,154.42. The two differ by five years of history, about 19% of the headline, and it is the figure most people misread.

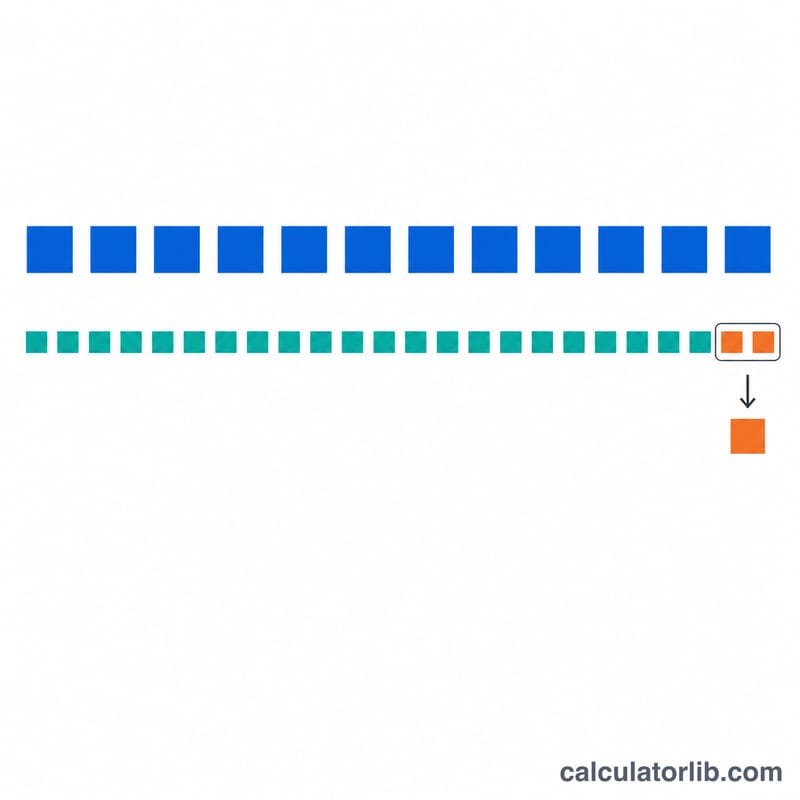
"Biweekly" is not biweekly. The schedule underneath is monthly; it adds half a payment every sixth month, which is 13 monthly payments' worth per year. Same annual money as a real biweekly plan, different timing — so do not expect it to match a lender's biweekly quote to the month. On the example loan it clears in 21 years and 2 months and saves $61,869.

The yearly extra lands 12 payments from now, not in December. It is applied on the 12th payment of the payoff schedule and every 12 payments after that — tied to when you start, not to the calendar, and not spread across the year.

Some rows disappear on purpose. The Monthly pay comparison row only shows when your new payment is identical every month — add a yearly or one-time extra and it vanishes, because there is no single figure to print. If nothing has been paid yet (remaining term equals the full term), the two Remaining rows are omitted too.

A tiny extra can save real money and still report zero. $1 a month on the example loan saves $393 in interest but not one whole month, so the payoff still reads 25 years, Time savings comes back blank rather than "0 months," and both percentage bars read 0%.

The two term boxes round differently. A fractional original term rounds up to the next whole month (10.51 years becomes 127 months), while the remaining-term boxes each round to the nearest whole (25.1 years stays 300 months). The months box is not capped at 11 — 24 years and 15 months is a legal 303 months.

Rejections are strict. A 0% rate is refused rather than treated as interest-free; a remaining term longer than the original is refused, compared in months, so 30 years and 1 month against a 30-year loan fails. Under the extra-payments option you need at least one positive extra and no negative ones — a −$100 monthly entry rejects the whole submission even with a valid $1,200 yearly extra beside it. Commas in the loan amount are fine; a currency sign is not.

Reading the schedule. The table always runs the full original term, so after the loan clears in month 267 the payoff columns show $0.00 out to month 360 — that is the loan being over, not missing data. The Principal column is the printed payment minus the printed interest, so it can sit a cent away from the change in the balance column. Past about 41 years of term the schedule is not drawn at all, though every summary figure is still calculated.
Twelve monthly payment blocks above twenty-six biweekly blocks, with two extra half-payments highlighted
Twenty-six biweekly half-payments equal thirteen monthly payments — one extra payment each year.

Questions people ask

Why does the balance it shows differ from my statement?

The balance is reconstructed from your original loan and the term left, assuming every payment so far was exactly on schedule. Extra payments you already made will move your real balance. Adjust the remaining term until the reported balance matches, then read the results.

Should I include taxes and insurance in the payment?

Nothing here asks for your payment — it derives the principal-and-interest payment from the loan itself. Escrow never touches principal, so leave it out of the extra-payment boxes too.

Monthly extra, yearly extra, or one lump sum — which wins?

Dollar for dollar, earlier money wins, because it stops accruing interest sooner. On the example loan, $500 a month saves $122,306; $1,200 once a year saves $33,461; a single $5,000 today saves $16,769. Consistency beats size: the monthly option puts in $6,000 a year and finishes 7 years and 9 months early.

Why is "Interest savings" a round dollar amount when the table shows cents?

The savings banner and the comparison bars round to whole dollars; the table below them keeps cents. Same figure — $122,306.21 becomes $122,306 in the banner. Percentages round to whole numbers the same way.

Is paying the mortgage off early actually the right move?

This answers the arithmetic only. Paying down a 6% mortgage is a guaranteed 6% return, which is strong — but weigh it against matched retirement contributions, higher-rate debt, and an emergency fund, and check your loan for a prepayment penalty.

How Different Payoff Strategies Compare

Every row below uses the same loan, so only the payoff strategy changes. Shared assumptions:

  • Original loan amount $300,000, original term 30 years, fixed note rate 6.5% per year.
  • Remaining term 27 years (324 payments), first remaining payment in September 2026.
  • Scheduled principal-and-interest payment \(M = \$1{,}896.20\) per month, from

$$M = 300{,}000\cdot\frac{r(1+r)^{360}}{(1+r)^{360}-1},\qquad r=\frac{6.5}{1200}=0.00541667$$

The balance today implied by 324 remaining payments is

$$B_{0} = 1{,}896.20\cdot\frac{1-(1+0.00541667)^{-324}}{0.00541667} \approx \$289{,}251$$

Interest below is interest on the remaining balance only (interest already paid in the first 3 years is not counted). Every extra dollar is assumed to be applied to principal in the month it is paid. The "biweekly-style" row is the common North American arrangement modelled as 13 full payments a year (an extra \(1{,}896.20/12 = \$158.02\) per month); a servicer that actually credits money every two weeks pays down marginally faster.

Strategy Extra paid per year Months to payoff Payoff date Interest paid (remaining term) Interest saved vs. baseline
No change (baseline) $0 324 (27 yr 0 mo) Aug 2053 ≈ $325,120 —
+$100 per month $1,200 285 (23 yr 9 mo) May 2050 ≈ $278,550 ≈ $46,570
+$500 per month $6,000 197 (16 yr 5 mo) Jan 2043 ≈ $181,340 ≈ $143,780
$1,200 once a year $1,200 286 (23 yr 10 mo) Jun 2050 ≈ $279,600 ≈ $45,500
$10,000 lump sum now $10,000 (one time only) 296 (24 yr 8 mo) Apr 2051 ≈ $281,700 ≈ $43,400
Biweekly-style (13 payments/yr) $1,896 (one extra payment) 267 (22 yr 3 mo) Nov 2048 ≈ $257,750 ≈ $67,400

Two patterns are visible and both follow directly from the arithmetic. First, $1,200 spread over the year beats $1,200 paid at year-end (285 months vs. 286, about $1,000 more interest saved) because each monthly instalment stops accruing interest sooner. Second, a one-time $10,000 saves less than $100 a month even though $10,000 is far more money up front — the recurring payment eventually contributes $27,000+ of principal. Comparing the last two columns row by row is the honest comparison: cost per year against interest avoided.

All figures assume the interest rate stays fixed for the whole remaining term, that no payment is missed or reduced, and that nothing else about the loan changes. On an adjustable-rate loan every number here would move with the next rate reset.

Advertisement

Mortgage Payoff Terms Defined

Term Definition
Principal The amount of money still owed on the loan itself, excluding interest — this is what an extra payment reduces and what the calculator drives to zero.
Original loan amount The sum borrowed at closing, entered as originalLoanAmount; it is used only to derive the scheduled payment \(M\), not as today's debt.
Current (remaining) balance What you owe today; the calculator reconstructs it as the present value of the remaining payments, \(B_{0}=M\cdot\frac{1-(1+r)^{-N}}{r}\), rather than asking you for it.
Original term The full repayment period the loan was written for (commonly 30, 25, 20 or 15 years), entered as originalLoanTermYears.
Remaining term The payments still ahead of you, entered as remainingTermYears plus remainingTermMonths, giving \(N\) months in the baseline schedule.
Scheduled payment (P&I) The fixed principal-and-interest instalment required by the note, computed here from the original amount, rate and term — not including taxes or insurance.
Monthly periodic rate The annual nominal rate divided by 12, \(r=\text{rate}/1200\) as a decimal, which is the rate actually charged on the balance each month in the amortization loop.
Note rate vs. APR The note rate is the interest rate written in the loan contract and is the correct input here; the APR is a disclosure figure that folds in certain fees and would overstate the interest actually charged on the balance.
Amortization The process by which each payment covers that month's interest first and applies the remainder to principal, so the principal share grows over time — the month-by-month table the calculator prints.
Interest saved Total interest under the baseline schedule minus total interest under the payoff schedule, over the remaining term only.
Lump sum A single one-time payment (field extraPaymentOneTime) applied at the first month, \(k=1\), of the projection.
Biweekly Paying half the monthly instalment every two weeks, which produces 26 half-payments = 13 full payments a year; the calculator models this as one extra payment spread across 12 months.
PITI vs. P&I PITI is principal, interest, taxes and insurance — the amount many borrowers actually remit; this calculator works only on P&I, so any escrow portion of your bill must be excluded from the inputs.
Escrow The account a servicer uses to collect and pay property taxes and insurance on your behalf; it is not part of the debt and is not modelled here.
Prepayment penalty A contractual fee for repaying early or above a threshold — restricted or banned in some jurisdictions and permitted in others, so check your own note; the calculator assumes no such fee.
Principal curtailment An extra payment applied immediately to reduce principal, which is what every extra amount in this model does.
Paid-ahead application The alternative treatment in which a servicer parks extra money toward your next instalment instead of reducing principal — this produces no interest saving and would invalidate the results shown.
Recast (re-amortization) A servicer re-calculating the required monthly payment over the original end date after a large principal reduction, which lowers the payment instead of shortening the term; this calculator always keeps the payment fixed and shortens the term.

What Your Payoff Result Actually Means

  1. Interest saved is a nominal, undiscounted total. The figure adds up dollars that would have been paid across decades and treats a dollar in 2050 as equal to a dollar today. It is not a present value, not inflation-adjusted, and not an after-tax number. A saving of, say, $46,570 spread over 24 years is a much smaller quantity in today's money than the same amount received now.
  2. The payoff date rests on two assumptions. First, that the interest rate stays fixed for the entire remaining term — on a variable or adjustable-rate loan the schedule changes at every reset. Second, that each extra payment is actually credited to principal in the month shown. If a servicer applies extra funds as "paid ahead" toward the next instalment rather than as a principal curtailment, the projected date and the interest saving do not occur.
  3. The required monthly payment does not go down. Extra payments buy a shorter term, not a lighter bill. The contractual instalment stays the same until the loan is gone — unless the lender performs a recast, which re-amortizes the reduced balance over the original end date and lowers the payment while giving up most of the term reduction. Recasting is offered at the servicer's discretion, often with a fee and a minimum principal reduction.
  4. Escrowed costs continue after payoff. Property taxes, homeowner's/buildings insurance, and any mortgage insurance or association dues are excluded from every figure here. When the loan ends, the escrow portion of your monthly outlay simply becomes a bill you pay directly; only the principal-and-interest portion disappears.
  5. Tax treatment can reduce the value of interest saved. In the United States, taxpayers who itemize may deduct qualifying mortgage interest, so avoiding a dollar of interest is worth less than a dollar to them — roughly \((1-t)\) of it, where \(t\) is the marginal rate. Most filers take the standard deduction and get no such offset, and other countries treat mortgage interest very differently (some allow relief, many allow none). The calculator reports pre-tax interest in all cases.
  6. The standard factual benchmark is the loan rate itself. Prepaying principal avoids interest at exactly the note rate, so the return on an extra payment, before tax and before any fees, equals the loan's rate — 6.5% in the comparison above. That is the number the result should be compared against; the calculator states the effect, not whether it is worthwhile for you.
  7. Results are servicer-specific and illustrative. Payment posting dates, day-count conventions, rounding, any prepayment penalty in your note, and the exact remaining balance on the servicer's books will all shift the totals slightly. This tool is a projection, not a payoff quote — a legally binding payoff figure, good only through a stated date, must come from the loan servicer.

This section is general information about how the calculation works, not financial, tax or legal advice, and it is not a recommendation for or against prepaying any particular loan. For decisions about your own mortgage, consult a qualified professional who can see your full situation and the terms of your note.

See also: Mortgage Payoff Calculator — a quick payoff-date estimate from your balance, rate and monthly payment.


Last updated:

Most popular in Financial

View all Financial calculators