

What this calculator does
This calculator gives the French tax value of a usufruct, of a right of use or habitation, and of the matching bare ownership. The values are shares of the full-ownership value of an asset, taken from the scale in article 669 of the Code général des impôts (CGI). It suits notaries, advisers, and families who are planning a gift with reserved usufruct, a sale of bare ownership, or a succession.
How to use it
Follow the form in order. Choose the type of right: lifetime usufruct, fixed-term usufruct, or right of use/habitation. Choose whether the usufructuary is a natural person or a legal entity. A legal entity can only hold a fixed-term usufruct. Enter the full-ownership value in euros. For a natural person, give the age either directly in completed years or through the birth date and transfer date (YYYY-MM-DD). For a fixed-term usufruct, enter the duration in years and extra months (0 to 11). Fields that do not apply to the chosen mode are ignored.
Formula
For a lifetime usufruct, with \(V\) the full-ownership value and \(p(a)\) the scale percentage for age \(a\):
$$U = \frac{V \times p(a)}{100}$$For a fixed-term usufruct, the share is 23% per started ten-year period, capped at the lifetime share for a natural person:
$$U = \frac{V \times \min\left(23 \times \lceil m/120 \rceil,\ p(a)\right)}{100}$$Here \(m\) is the duration in months. For a right of use or habitation, \(D\) is its value:
$$D = \frac{V \times 0.6 \times p(a)}{100}$$The bare ownership value is \(NP = V - U\), or \(V - D\) for a right of use or habitation.
Conventions and assumptions
- Scale edition: the article 669 scale as amended by the 2004 Finance Law, valid for transfers on or after 1 January 2004. In dates mode, earlier transfers are refused.
- Age: completed years on the transfer date, so the year counts once the birthday has been reached.
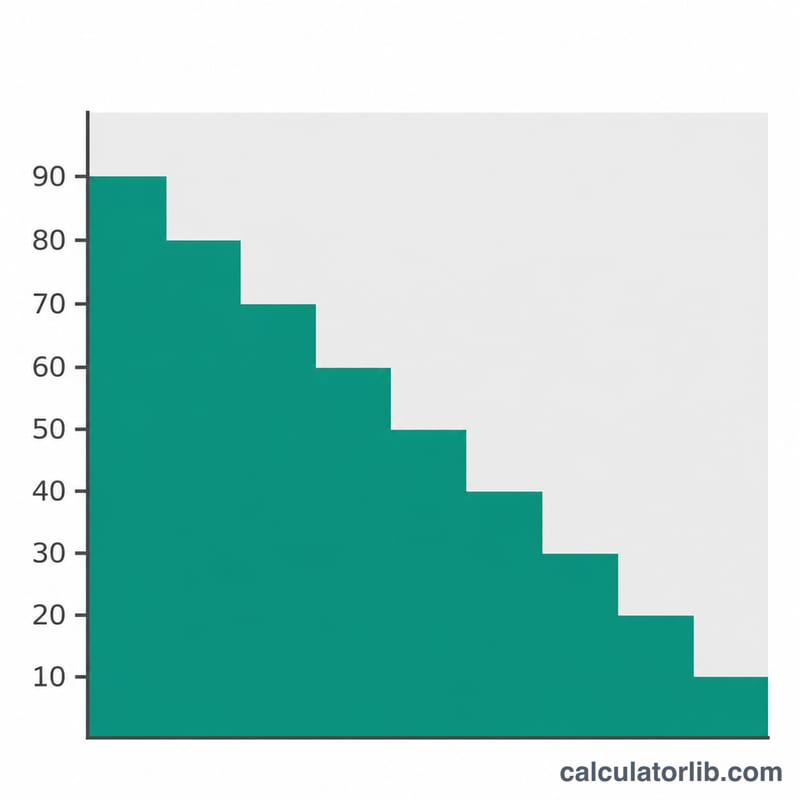
- Band edges: under 21: 90%; under 31: 80%; under 41: 70%; under 51: 60%; under 61: 50%; under 71: 40%; under 81: 30%; under 91: 20%; 91 and over: 10%. Age exactly 91 is placed in the last band because it is not less than 91.
- Fixed-term periods: every started ten-year period counts in full, with no pro-rata, so 10 years gives 23% and 10 years 1 month gives 46%.
- Cap: for a natural person, a fixed-term value never exceeds the lifetime value for that age.
- Legal entity: only fixed-term usufructs of up to 30 years are allowed, with a maximum of 69%. Age is ignored.
- Right of use or habitation: 60% of the lifetime usufruct percentage (art. 762 bis CGI).
- Rounding: percentages are exact integers. Euro amounts are shown to two decimals. All amounts are in EUR.
Worked example
A natural person aged 65 holds a lifetime usufruct over an asset with a full-ownership value of 300,000 EUR. At age 65 the person falls in the under-71 band, so the share is 40% and the bare ownership share is 60%.
$$U = \frac{300000 \times 40}{100} = 120000\,\text{EUR}$$$$NP = 300000 - 120000 = 180000\,\text{EUR}$$Age used: 65 years; lifetime share: 40%; ten-year periods counted: 0; cap applied: no.
How to read the result
The usufruct value and the bare ownership value add up to the full value. They are the bases on which registration duties are computed for gifts and successions. The result is a tax valuation under the scale, not a market price, and it does not model every special case. Joint usufructs without stated shares are not automated: split the asset into equal parts and run the calculation once per usufructuary. The transitional cap for bare ownership given before 2004 is not modelled. For a surviving spouse's habitation right, use the date one year after the death as the transfer date. Confirm important transactions with a notary or the tax authority.
FAQ
Which age is used for the scale?
The age in completed years of the usufructuary on the transfer date. A person who turns 61 on the transfer date is already in the under-71 band.
How is a fixed-term usufruct valued?
At 23% of the full value for each started ten-year period, but never above the lifetime usufruct value for a natural person.
What is the maximum for a legal entity?
A legal entity can hold a usufruct for at most 30 years, so the value is at most 3 × 23 = 69%.
How is a right of use or habitation valued?
At 60% of the lifetime usufruct value for the holder age, for example 24% at age 65.
Does the scale apply to transfers before 2004?
No. This tool covers only the scale in force for transfers from 1 January 2004.
Is the result legal advice?
No. It is an estimate of the tax valuation based on the published scale.
Sources
- BOI-ENR-DMTG-10-40-10-50 – Évaluation des biens transmis – Démembrement du droit de propriété, Direction générale des Finances publiques (BOFiP-Impôts), 2013.











