What this calculator does
This calculator estimates the tax value of a usufruct in Spain and of the matching bare ownership (nuda propiedad). It follows the valuation rules of the consolidated Transfer Tax Act (TRLITPAJD, art. 10.5). It covers lifetime usufructs, temporary usufructs and lifetime usufructs that are also time-limited. It also covers rights of use and habitation. It suits buyers, heirs, donees, advisers and anyone preparing a tax return who needs a quick valuation.
How to use it
Enter the following in order:
- Full ownership value of the asset in EUR. For real estate this is normally the cadastral reference value, or the declared or agreed value if higher.
- Type of right: usufruct, or right of use/habitation.
- Duration: lifetime, temporary, or lifetime and also temporary.
- Age of the usufructuary in completed years, used for lifetime rights only.
- Duration in whole years, used for temporary rights only.
Inputs that do not apply to the chosen duration are ignored.
Formula
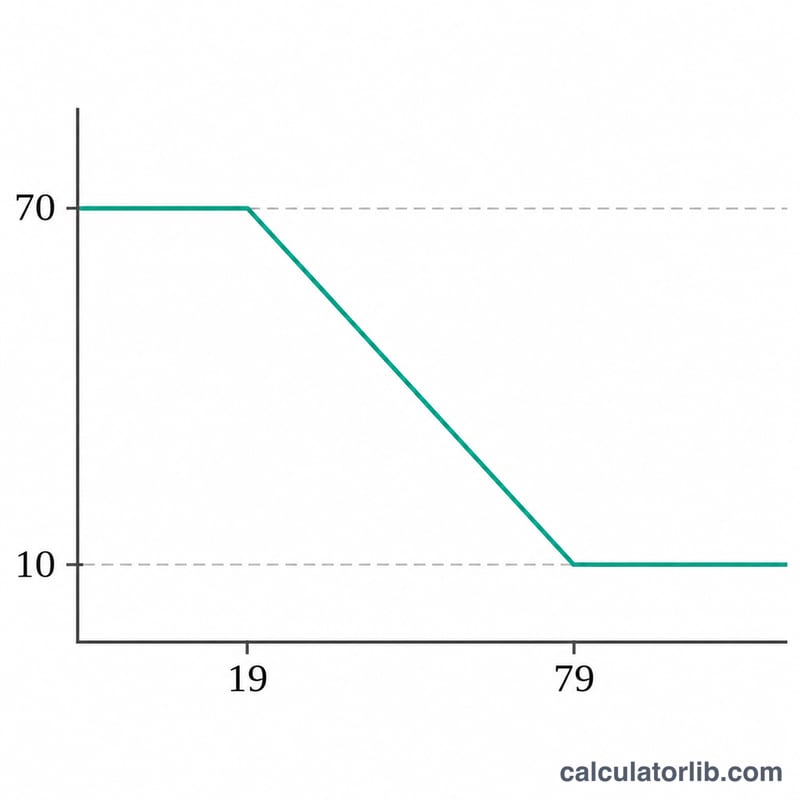
$$p_v = \min(70,\max(10,\,89-\text{age})),\quad p_t = \min(70,\,2n),\quad p=\max(p_v,p_t)$$
$$U = B\times\frac{p}{100},\qquad NP = V - U$$
Here \(V\) = full value, \(B\) = valuation base (\(V\) for usufruct, \(0.75V\) for use/habitation), \(p_v\) = lifetime percentage, \(p_t\) = temporary percentage, \(n\) = years of duration, \(p\) = percentage applied, \(U\) = value of the right and \(NP\) = value retained as bare ownership. For a purely lifetime right \(p=p_v\); for a purely temporary right \(p=p_t\).
Conventions and assumptions
- Lifetime: 70% if the usufructuary is under 20, then 1 point less for each extra year, with a 10% floor. This equals 89 minus age, clamped between 10 and 70. Age is in completed years.
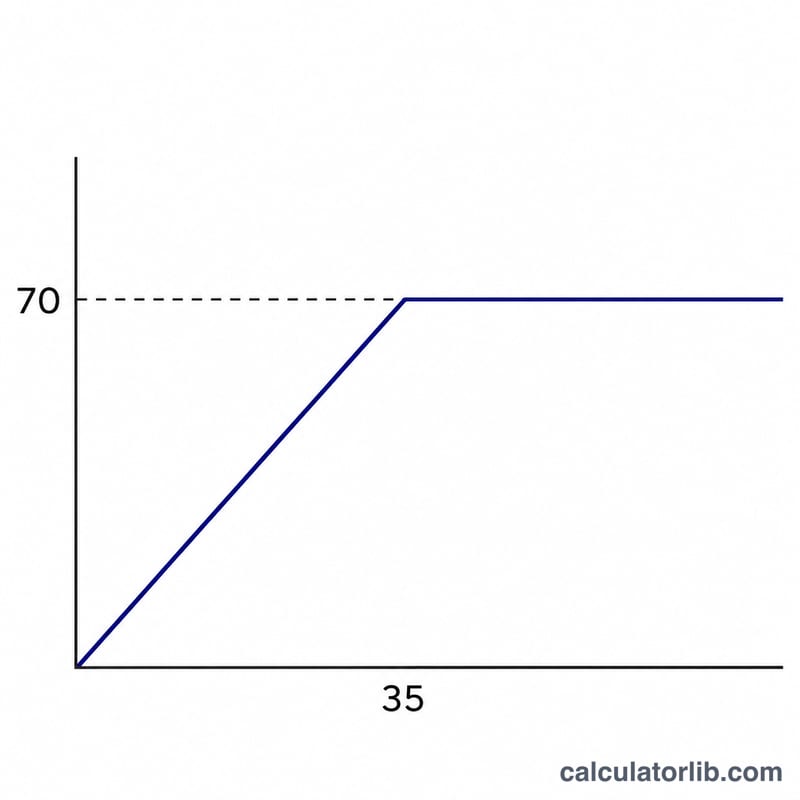
- Temporary: 2% per year, capped at 70%. Only whole years are accepted.
- Lifetime and temporary: both percentages are computed and the higher one is applied, because it gives bare ownership the lower value. A tie counts as lifetime.
- Bare ownership is the full value minus the usufruct value.
- Use and habitation apply the same percentages to 75% of the asset value. The owner residual shown is the full value minus the right value, a presentation choice.
- Monetary values are unrounded internally and shown to 2 decimals in EUR. The statute sets no rounding.
- The full value is entered by the user; the tool does not determine it.
- Common state rules apply. Foral regimes (Basque Country, Navarra) and regional variations are not modelled.
- A usufruct for a legal entity lasting over 30 years or indefinitely is taxed as full ownership under a resolutory condition (art. 10.5.a). This case is not modelled.
- The age is assumed to be measured when the right is constituted or acquired.
Worked example
A property has a full value of €200,000. A lifetime usufruct is constituted for a person aged 65.
$$p_v = 89 - 65 = 24\%$$
$$U = 200{,}000\times\frac{24}{100} = 48{,}000\ \text{EUR}$$
$$NP = 200{,}000 - 48{,}000 = 152{,}000\ \text{EUR}$$
The right is 24% of the full value and the bare ownership 76%. The valuation base is 200,000 EUR, the temporary percentage is not applicable (0) and the rule applied is lifetime.
Reading the result and limitations
The usufruct value is the amount used as the tax base for the right, and the bare ownership value is the base for the remaining title. The result is a statutory valuation, not a market appraisal. It does not compute the tax due, which depends on the tax involved, reductions and the region. The inheritance and gift tax rule (Ley 29/1987) is generally understood to mirror these percentages, but this tool is built on the TRLITPAJD text. Confirm the treatment with a tax adviser or the competent regional tax office before filing.
FAQ
How is a lifetime usufruct valued?
At 70% of the full value if the usufructuary is under 20. The percentage falls by one point for each additional year, never below 10%. That is 89 minus age within the 10 to 70 range.
How is a temporary usufruct valued?
At 2% of the full value for each year of duration, up to 70%. A duration of 35 years or more reaches the cap.
What if the usufruct is lifetime but also limited in years?
Both rules are computed and the one that gives the bare owner the lower value, meaning the higher usufruct percentage, is applied.
How are use and habitation rights valued?
The usufruct rules are applied to 75% of the asset value. At age 65 this is 24% of 75%, or 18% of the full value.
Does the calculator work for Basque Country or Navarra?
No. Foral regimes are preserved by the law and may differ, so only the common state rules are modelled.
Sources
- Real Decreto Legislativo 1/1993, Texto refundido de la Ley del Impuesto sobre Transmisiones Patrimoniales y Actos Jurídicos Documentados (consolidated), Agencia Estatal Boletín Oficial del Estado, art. 10.5 as worded since 2021.
- Ley 29/1987, del Impuesto sobre Sucesiones y Donaciones (consolidated), Agencia Estatal Boletín Oficial del Estado, 2022 (context only).